Category Archives: Blog

Is Your Agent Marketing Your Home, or Marketing Themselves?

By Brendan Leahy, Naked Real Estate® 

I should say up front that I market myself too. I write these articles, I post on social media, and I have a commercial interest in you thinking well of me. So take what follows as an argument you should test against me as much as anyone else. 

I was at a kitchen table for an appraisal not long ago when the owner asked me something I am hearing more and more. 

“How many social media followers do you have?” 

I showed her, then asked why it mattered to her. Another agent had been through and told her he had around seven thousand followers across Instagram, Facebook and TikTok. 

I understand why that sounds like something. Big following, big reach, more buyers, more competition, better price. That is the chain of reasoning and each link sounds sensible. 

The problem is the first link.

A follower is only worth something if they could buy your home 

Someone watching a property video in Sydney, London or Shanghai is not buying in Bedfordale, Roleystone, Kelmscott, Mount Nasura, Mount Richon or Seville Grove next weekend. 

That is not an argument against social media. Used properly it is a genuinely useful part of a campaign, and paid targeting, retargeting and database marketing can put your home in front of exactly the right people. 

It is an argument against treating an agent’s popularity as a selling strategy. 

I would rather have three hundred local followers who live here, know the market and watch what sells, than ten thousand who have no connection to the home. The goal is not attention. It is enquiries, inspections, offers and competition between buyers. 

Views do not pay the seller 

A video can get twenty thousand views and still fail. 

If those views produce no qualified enquiry, no private inspection, no buyer conversation and no offer, then the video helped the agent more than it helped the seller. It entertained the algorithm. 

Sellers do not get paid in likes. They get paid at settlement. 

So the question to put to any campaign is not how it performed as content. It is whether it created buyer competition for your property. 

I am not against video. We were early to it. 

We have been making property videos since 2013, back when most agents used video only on high-end homes. We made it standard because buyers look at video as closely as they look at photos. 

Video shows what photos cannot: how a home flows, how rooms connect, how the land is used, the outlook, the access, the sheds, the feel of standing in the place. Floor plans do the same job from a different angle. Buyers want to understand how a home works before they give up a Saturday to inspect it. 

And it does not need to be long. Most property videos should be a clear walkthrough that explains the home and makes the buyer want to see it, and past a few minutes you are usually not selling harder, you are asking more of the buyer’s attention than the job requires. Our videos from 2013 mostly ran between one and two minutes. That was deliberate then and it still holds. 

Good photos, video and floor plans all serve one purpose. Selling the home. 

Is the home the hero? 

This is the simplest test there is. Watch the video and ask who it is about. 

A good property video makes the right buyer understand the home and feel something about it. In the Hills that might be the usable land, the workshop access, the valley outlook, the quiet street, the fireplace, the privacy, the school run, the layout, or the specific reason a family would stretch to buy it. 

There is room for personality and there is room to be creative. Some homes suit it. But the property should not become the backdrop to somebody’s personal brand. 

Every one of our videos is captioned 

This sounds like a small thing. It is not. 

Plenty of buyers watch property videos with the sound off. At a desk at work having a quick look at what is open on the weekend. On the train home. On the couch with the television going. If your video only works with audio, those buyers get half of it. 

It still surprises me how many agents skip this. 

There is a second benefit. Search engines read captions, so an accurate caption file means the suburb, the street and the features of your home are indexed as text. Auto-generated captions are not good enough for that, because they routinely mishear street and suburb names, which are the exact words worth indexing. 

It costs a bit of time per video. It costs the seller nothing, and it works whether the buyer has the sound on or not. 

The numbers that actually matter 

When you are choosing an agent, ask about the numbers connected to a result rather than to an audience. 

How many enquiries did comparable properties attract? How many inspections, and how many second inspections? How many buyers were followed up, and how? How many offers were created? How was competition between them handled? How did the final price compare to the original guide? How many buyers missed out and are still looking? 

I will be straight with you: those are the numbers I am strong on, so of course I am pointing you at them, just as the agent leading with follower count is

pointing you at his. The difference I would ask you to weigh is which set of numbers actually ends up in your bank account. Marketing creates attention. Follow-up creates competition. Negotiation creates the result. An agent who is strong at the first and weak at the other two will produce a busy campaign and a disappointing number. 

Five questions worth asking 

If an agent leads with their following, ask these: 

  1. How many of your followers are plausibly in the buyer pool for a home like mine? 
  2. Will my property be marketed only to your followers, or targeted beyond them? 
  3. In your campaigns, what matters more: views, enquiries, inspections or offers? 
  4. Can you show me how a recent campaign turned attention into buyer action? 
  5. In the video, will my home be the hero, or will you be? 

A good agent will not be offended by any of that. They should be able to answer all five without hesitating, and if they cannot, you have learned something useful for the price of asking. 

Frequently asked questions 

Do social media followers help sell a house? 

Only the followers who could actually buy your home in your area. Reach for its own sake does not pay the seller; a video seen by thousands of people with no connection to your suburb creates no competition. Local, targeted reach and proper follow-up matter far more than a big follower count. 

How do I choose a real estate agent in the Perth Hills? 

Judge them on numbers connected to results, not to an audience: enquiries, inspections, second inspections, offers created, how buyer competition was handled, and how final prices compared to the original guide. An agent strong on attention but weak on follow-up and negotiation produces a busy campaign and a disappointing price. 

Does video actually help sell property? 

Yes, when it is about the home. Good video shows what photos cannot, how a home flows, the land, the outlook, the access, and helps a buyer decide the property is worth inspecting. Captions matter too, because a lot of buyers watch with the sound off. The test is simple: is the home the hero, or is the agent? 

Is a longer property video better? 

Usually not. Past a few minutes you are generally asking more of a buyer’s attention than the job needs, though some properties, large acreage in particular, genuinely need the extra time to show the land and the outbuildings properly. A clear walkthrough that makes the buyer want to see the home in person does more than a long video that performs well as content but produces no enquiry. 

Selling in the Perth Hills or Foothills? 

If you are selling in Bedfordale, Roleystone, Kelmscott, Mount Nasura, Mount Richon or Seville Grove, do not choose an agent on a follower count. Ask how they will reach the buyers who could actually buy your home, and what they will do once those buyers put their hands up. 

That second part is where the money is. 

Book a free Perth Hills and Foothills property appraisal. If you want to see how we handle buyer competition once interest appears, read Auction vs Private Treaty vs Select Date Sale® and our Best Service Guarantee

Truth. Strategy. Sold. 

About the author: Brendan Leahy has been selling homes throughout the Perth Hills and Foothills since 2002, with more than 1,500 personal sales. Learn more about Brendan Leahy and the Naked Real Estate story.

photo of a garden in a Mount Nasura property

What Is My Mount Nasura Property Worth?

By Brendan Leahy, Naked Real Estate®

Here is a Mount Nasura sale that still makes the point for me. The automated valuation said around $600,000 to $650,000. Another agent thought $700,000 was the ceiling. It sold for $835,000. Same house, three very different numbers, and I will come back to why below.

First, my interest: I sell property in Mount Nasura, so of course I would like you to pick up the phone. Take what follows with that in mind, and test it.

The biggest reason those three numbers were so far apart is the mistake almost everyone makes here: treating Mount Nasura as one market. It is not, and the differences sit inside a surprisingly small area. Older homes on smaller blocks closer to Armadale. Larger properties around 1,200 square metres and half-acre blocks. Homes looking across the valley. Homes with city and coastal plain views. Properties within walking distance of the hospital, the shops and the train station. And occasionally something that does not fit the Mount Nasura mould at all.

Which side of the hill you are on

A median cannot tell where you sit in the suburb. Buyers can, and it changes what they will pay.

The lower parts tend towards older homes on smaller blocks with excellent access to Armadale’s shops, the hospital and public transport. Move higher and both block sizes and housing styles change. On the southern side of Blackwood Drive and nearby, properties can have attractive valley outlooks. On the northern side, some homes look towards the city and the coastal plain, which is a genuinely different living environment from the west-facing outlook you get across much of the Darling Scarp. Around the eastern side towards Paterson Road, the outlook turns towards the Brookton Valley.

Before anyone walks through the front door, position within the suburb has already changed who the likely buyer is.

Find out what your property is worth by booking a free appraisal.

What moves the number here

Position within the suburb. Block size, slope and usability. City, coastal or valley views. Orientation. Sewer or septic. Age and condition. Renovations. Access. Proximity to the hospital, the shops and the train station. Schools. Outdoor living. Privacy. What else is currently on the market. And the type of buyer the property is likely to attract.

Then one more question that matters more than people expect: does this property fit the comparable sales at all?

The 320 square metre home that did not fit

The sale I opened with makes that point better than any explanation.

It was not on a half-acre block. It was not on 1,200 square metres. The original block had been subdivided and this home sat on roughly 320 square metres.

On paper that made it very hard to compare with most of the suburb. The automated valuation put it somewhere around $600,000 to $650,000. Another agent had been through and thought around $700,000 would probably be the ceiling.

I saw it differently.

The owners had designed the home around the smaller site and done it well. Two storeys, three bedrooms, two bathrooms, and the presentation was as good as I have seen. The design worked with the block rather than apologising for it.

More importantly, there was a buyer for whom 320 square metres was not a compromise. Close to Armadale Hospital. Public transport nearby. Walking distance to the train station and the shopping centre. For someone who wanted a beautifully presented, low-maintenance home in the hills without a half-acre to manage, this offered something almost nothing else in the suburb did.

So I did not think we should price it by taking larger Mount Nasura homes and discounting for less land.

My recommendation was to go to market from $750,000.

Twenty-three groups, and no offer

We ran it as a Select Date Sale®. The first home open brought twenty-three groups through.

And no offer that weekend.

It is easy to tell property stories where everything lands in twenty-four hours. Real selling does not always work like that. We ran private viewings through the week and opened again the following weekend.

By Monday night we had six offers, running from about $750,000 up to the one the owners accepted at $835,000.

Set that against where we started. An automated estimate of roughly $600,000 to $650,000. Another agent’s ceiling of about $700,000. A sale at $835,000.

Was the algorithm wrong?

I want to be fair about this. An automated system can only work with the comparable sales available to it. If almost every property around this one is substantially different, what exactly is it supposed to compare against?

The computer was not stupid. The property did not fit the dataset.

A human appraisal could weigh things that do not reduce to bedrooms, bathrooms and land area. The design. The presentation. The low-maintenance proposition. The walkability. And most of all, the specific buyer who wanted that combination and could not find it anywhere else in the suburb.

Want to know the value of your Mount Nasura property? Book a free appraisal

Views are not a fixed dollar amount

A home with an uninterrupted outlook towards the city and the coastal plain is not automatically comparable with one two streets away without it. Same for the valley outlooks.

But I would not add a set figure for “views” either. What matters is which rooms have them, whether they can be built out, the orientation, whether the outdoor living actually uses them, the privacy, and how buyers respond when they physically stand there and look.

The location changes the buyer, not just the price

Proximity to Armadale Hospital is a good example. For some buyers that is enormously convenient and worth paying for. For others it is exactly what they are moving away from, because they want land and separation.

Neither buyer is wrong. They are different markets, and the job is working out who is likely to value what you actually have.

What the $835,000 does not mean

It does not mean everyone should renovate heavily before selling.

Those owners had built a home where design and presentation were fundamental to the whole proposition. On a different property, spending $100,000 before sale could be entirely wasted.

The question is never whether renovations will make the house nicer. Of course they will. The question is whether the buyers you are targeting will pay back more than you spend.

Let Brendan Leahy tell yu what your property is worth and put a strategy together to sell your Mount Nasura home

Frequently asked questions

What is the average property worth in Mount Nasura?

Averages give you context and not much else. The suburb contains enough variation in blocks, views, position and housing style that a median can be a poor guide to any individual property.

Do city views increase value in Mount Nasura?

They can. How much depends on the quality of the outlook, whether it is permanent, the orientation, and whether the home is designed to use it.

Does a smaller block reduce value?

Not necessarily by as much as people assume. A well-designed, low-maintenance home close to amenities can attract a buyer pool that larger properties in the same suburb do not reach.

Are online valuations accurate in Mount Nasura?

They work reasonably on standard properties with good comparable sales. They become unreliable when the land size, views, position or design fall outside the dataset.

How do I get my Mount Nasura property appraised?

Combine recent comparable sales with an inspection that considers the exact position, the outlook, the land, the improvements, the presentation and what else buyers can currently choose from.

About the author: Brendan Leahy has been selling homes throughout the Perth Hills and Foothills since 2002, with more than 1,500 personal sales. Learn more about Brendan Leahy and the Naked Real Estate story

Truth. Strategy. Sold.

An aerial view of Bedfordale in Western Australia at sunset

What Is My Bedfordale Property Worth?

By Brendan Leahy, Naked Real Estate®

I make my living selling Bedfordale property, so read this knowing I have an interest in you calling me. What I can offer in return is that the story below starts with me telling a seller not to spend more than $60,000 preparing her home for sale, because I did not believe she needed to.

If you want to know what your Bedfordale property is worth, start here: Bedfordale is not one market.

Two properties that look identical on paper can be worth very different money. Four bedrooms on five acres, both of them. One has five genuinely usable acres. The other is steep enough that only a fraction of it is practical. One has scheme water. The other runs on tanks, a bore and a dam. One has a proper workshop and good truck access. The other has a beautiful view and nowhere to put anything.

And sometimes the house is not the most valuable part of the property at all.

Why Bedfordale is hard to compare

There are several different Bedfordale markets sitting inside the one postcode.

Around Wallangarra and nearby, lifestyle and equestrian properties commonly sit on roughly three to six acres. Around Cairns Road, Carradine Road and the older rural parts, blocks run to ten acres and considerably more. Then there are the newer lifestyle estates, homes on roughly 3,000 to 4,000 square metres, often with scheme water and a modern build.

Those attract three different buyers with three different budgets and three different priorities.

Before I even walk through the house I am looking at how much of the land is genuinely usable, the slope, the access, the water and where it comes from, the sheds, the fencing, any equestrian infrastructure, the outlook and orientation, the privacy, bushfire considerations, the age and condition of the home, vehicle access, zoning, which pocket of Bedfordale it sits in, and what else buyers can choose from that month.

A suburb median knows none of that.

Find out how much your Bedfordale home is worth, ask for an appraisal

Does more acreage mean more money?

No. Usable acreage matters more than acreage.

Someone buying for horses will often pay more for level, well-fenced land with reliable water and good access than for a larger block that is steep and heavily treed. Another buyer wants the opposite, and will pay a premium for bushland, privacy and elevation.

Which is why price per acre is close to meaningless here. The land has to be understood in terms of what a buyer can actually do with it.

Water changes the number

Some Bedfordale properties have scheme water. Others run on tanks, bores, dams, or some combination.

Two otherwise similar properties can therefore be offering buyers completely different propositions. A good bore or a dam that does not run dry is genuinely valuable to someone keeping animals or establishing gardens.

But you cannot just tick a box marked bore. Capacity and reliability are the whole question.

Fifteen acres near Churchman Brook

One Bedfordale sale has stayed with me because of how far apart the opinions were.

I was asked to appraise about fifteen acres for a long-time owner. She and her husband had built the home roughly forty-five years earlier and it was still largely original. Dated kitchen, dated bathrooms, presentation that matched the era. She knew all of that.

Another agent had told her to spend more than $60,000 on the kitchen and bathrooms before going to market.

I told her not to touch it.

My reasoning was simple. Replace the kitchen and bathrooms and the rest of a forty-five year old house is still forty-five years old. Then what? Flooring. Paint. Lighting. Window treatments. Sixty thousand becomes a lot more, with no guarantee any of it comes back.

More to the point, I did not think the house was what would sell the property.

The land was. Close to Churchman Brook Dam, looking straight down the valley, north facing. For fifteen acres in Bedfordale it was unusually level and usable. Excellent water, including a good bore and a soak-fed dam that held through summer. And a genuine relationship between the home and the land, where you could sit in the kitchen, look through the French doors and see all the way down to the dam.

Rural zoning gave it appeal to buyers wanting animals, subject to the usual planning requirements.

Those were the things to sell. Not a new kitchen.

The appraisals were $400,000 apart

The automated valuation could not produce a meaningful figure, because it could not find enough comparable sales to work from.

The opinions she had from agents ranged from about $580,000 to close to $1 million. Same property. A gap of roughly $400,000.

I did not think anything over $900,000 was realistic in that market. But I also thought that focusing on the age of the house would badly undervalue what was actually rare about the place.

We launched with Select Date Sale® from $800,000, and the marketing led with the land, the water, the outlook and the position rather than pretending the house was something it was not.

It did not sell in the first weekend. It took about five weeks before an offer came in that she was happy to accept.

It sold for $897,000.

What I liked most was what happened after. The sale gave her enough to move into a riverfront unit in town. No more fifteen acres to look after, and a walk along the river every afternoon, which was the part she talked about.

Ask us for a free appraisal on your Bedfordale property’s value

Should you renovate before selling in Bedfordale?

Sometimes. Not automatically.

The question I ask is whether buyers will pay back more than you are about to spend.

Cleaning, gardens, maintenance and fixing obvious defects are usually worth doing and rarely cost much. Spending $60,000 or $100,000 because someone told you every house needs a new kitchen is a different proposition entirely.

Sometimes the buyer wants to renovate it themselves. Sometimes the value is in the land and the house is simply adequate. And sometimes a partial renovation makes everything you did not touch look worse by comparison.

It is a property by property decision.

Where online valuations struggle here

Automated valuations are not useless. In a suburb with hundreds of similar homes on similar blocks they have plenty to work with.

Bedfordale is not that suburb. An algorithm can read land size, bedrooms, bathrooms, sale history and nearby sales. It cannot tell you whether five acres are usable, whether the bore is any good, whether the workshop is worth anything, whether the access works for a truck and float, or how buyers react when they stand on the place.

Treat the estimate as information. It is not a strategy.

The better question

Start with the data. Look at recent sales and at what is competing for buyers right now. Then go past it and ask which of those sales are genuinely comparable, and what your property has that they did not.

After more than 1,500 personal sales since 2002, the properties that need the most judgement are always the unusual ones. Bedfordale has plenty. That is part of why people live here, and it is also why local knowledge matters when it comes time to sell.

Get the benefit of a local agent’s knowledge by requesting an appraisal now.

Frequently asked questions

How accurate are online property valuations in Bedfordale?

They are a starting point. Acreage, land usability, water, outlook and the sheer variety of Bedfordale property make automated comparison difficult, and in some cases the system cannot find enough comparable sales to produce a figure at all.

Does more acreage always mean higher value?

No. Usability, slope, access, water and buyer appeal usually matter more than the number of acres.

Should I renovate my Bedfordale home before selling?

Not automatically. The likely lift in price has to justify the cost, the time and the risk. Sometimes the land is the product and the house is not what buyers are paying for.

Do sheds and workshops add value?

They can, particularly when well built, accessible and relevant to the likely buyer. A shed that dominates the usable land can work against you.

Does a bore or dam increase value?

Reliable water is a genuine attraction on Bedfordale acreage, but it depends on capacity and reliability rather than simply having one.

How do I get an accurate Bedfordale appraisal?

Start with comparable sales, then assess what those sales cannot capture: land usability, water, outlook, improvements, position within the suburb and who is currently buying.

About the author: Brendan Leahy has been selling homes throughout the Perth Hills and Foothills since 2002, with more than 1,500 personal sales. Learn more about Brendan Leahy and the Naked Real Estate story

Truth. Strategy. Sold.

Auction vs Private Treaty vs Select Date Sale®: What Actually Works in the Perth Hills?

By Brendan Leahy, Naked Real Estate®

Before you read another word, you should know that one of the three methods I am about to compare is ours. Select Date Sale®⁠ is a Naked Real Estate® method. I have a commercial interest in you choosing it.

So I am going to do the fair thing: tell you where it is the wrong choice, and explain how it actually works rather than just telling you it is better.

I have been selling property in this patch since 2002, with more than 1,500 personal sales. Here is my honest read on the three options.

Private Treaty

Your home is listed with a price, a range or a from-price. Buyers make offers. You negotiate. It is simple, familiar, and buyers understand it immediately.

Its weakness is not the price on the sign. It is what happens after the first offer arrives. Most private treaty sales become a one-on-one negotiation between the seller and whoever moved first. If two other buyers were interested but slower, they often never get the chance to compete, because the property is under offer before they are ready.

The money is not usually lost at the pricing stage. It is lost in the fortnight after the first offer.

Private treaty suits you when your home is easy to price against recent comparable sales, when buyer demand is steady rather than competitive, and when you would rather have a straightforward process than push hard for every last dollar.

Auction

A public bidding process on a set day. Urgency, transparency, and a clear finish line.

Start with what auction genuinely does better, because it is real. If bidding reaches your reserve, the winning bid is unconditional and binding the moment the hammer falls. No finance clause, no building-inspection out, no subject-to-sale. Neither private treaty nor our own method can promise you that. The catch is that it only holds if the bidding gets there. If it does not, the property passes in and you are negotiating with the highest bidder anyway, having spent the campaign and told the market it failed to sell.

One thing to be clear about, because it is often misunderstood: WA has no cooling-off period on any residential sale unless the parties agree to write one in. That is true whether you sell by auction, private treaty or our method, so it is not an auction advantage and I am not going to pretend it is one.

Auction has two real weaknesses in this market.

The first is the buyer pool. A lot of Perth Hills and Foothills buyers need finance approval, a building inspection, a subject-to-sale condition, or a settlement date that lines up with their own move. Auction asks them to bid unconditionally. Some of them simply will not turn up, and you do not know which ones you lost.

The second is structural. At auction, the buyer who gets pushed to their true limit is the underbidder. The winner only has to beat them by one bid. Say the underbidder stops at $995,000; the winner buys at around $1,000,000. They may have been prepared to pay considerably more. You will never know, because the auction stopped asking the moment it had a winner.

Auction suits you when the market is hot, when your likely buyers are genuinely ready to go unconditional, when the property is straightforward enough for public bidding to find its level, and when a certain, binding result matters more to you than trying to extract the top bidder’s full limit.

Select Date Sale®

Here is the mechanic, in plain terms.

The property is listed with a from-price or a price range, chosen at listing. Buyers register their interest and inspect. When an offer arrives that you are prepared to consider, every registered buyer is told that an offer is on the table and invited to submit their best and final.

They are not told the amount of that offer. They are not told your reserve. They are not told what anyone else has put forward. And there is one round only, so if their offer is the one you choose, they cannot be outbid afterwards.

We do not counter-offer. Counter-offers invite a haggle, and a haggle usually moves the seller down rather than the buyer up. If an offer is not the one, we say so and let the buyer decide whether to come back stronger.

The date is yours. It might be tomorrow if a strong offer arrives early. It might be three weeks away. If no offer reaches a level you are prepared to accept, the home stays on the market. There is no artificial deadline. The trade-off, and it is worth naming, is that unlike auction the accepted offer can still carry conditions, so you gain flexibility and a wider buyer pool but give up the guaranteed unconditional finish auction delivers when it reaches reserve.

More than 730 sellers across the Perth Hills and Foothills have sold this way since 2015.

What the difference actually looks like

A recent Perth Hills home drew five offers. The best was just over $1.86 million. The second best was around $1.82 million.

Now run the same buyers through an auction. The underbidder stops at roughly $1.82 million. The winning bidder takes it at the next increment, call it $1.825 million. The seller banks around $35,000 less.

I want to be careful here, because the honest version matters more than the impressive one. Those same buyers might have bid differently in a room. Nobody can run both processes on the same house. But the gap between first and second is the money a bidding contest hands back to the winner, and in that sale it was real. That is the point of the example, not a promise that every seller will see the same gap.

It is also not always $35,000. Sometimes the top two offers are $2,000 apart and the method makes almost no difference at all.

Where Select Date Sale® is the wrong choice

If there is only one interested buyer, it does nothing. Competition you do not have cannot be created by a process. In a quiet market, or on a home with a narrow buyer pool, you are better off negotiating hard with the one buyer you have.

If your home is easy to price and there are five near-identical recent sales in the street, the extra process is probably not earning its keep.

If you want a binding, unconditional result the day the hammer falls, and you are confident the bidding will reach reserve, auction gives you that certainty and this does not.

And if you would rather counter-offer and haggle, this is not for you, because we do not.

The question to ask any agent

Not

“what price will you put on my home”.

Ask this instead:

If three buyers want my home, what exactly will you do to make sure each one submits their strongest position?

Then listen for a process. A specific sequence of steps. If you get adjectives instead of a mechanic, be careful, because that is where the money is made or lost, and it happens after the photos are done and the sign is up.

Frequently asked questions

Is auction or private treaty better for selling a house?

Neither is better in the abstract; it depends on your property and your buyers. Auction can drive strong competition in a hot market and, if it reaches reserve, gives a binding unconditional result, but it excludes buyers who need finance, inspections or a subject-to-sale, and if bidding falls short the home passes in. Private treaty is simple and familiar but often collapses into a one-on-one negotiation with the first offer, so slower buyers never compete. Match the method to the home, not to what the agency prefers to sell.

What is a Select Date Sale®?

It is a method that lists with a from-price or range, then, when a genuine offer arrives, invites every registered buyer to submit one best-and-final offer without knowing the other offers or the reserve. There is one round, no counter-offers, and the sale date is set by when a strong offer lands rather than by an artificial deadline. It is designed to make interested buyers compete rather than letting the first mover negotiate alone.

Can I lose money selling at auction?

You can leave money on the table two ways. If bidding does not reach your reserve, the property passes in, you have paid for the campaign, and the market now knows it did not sell, which weakens your hand in the negotiation that follows. And even when it does sell, the winner only has to beat the underbidder by one increment, so the top bidder may pay less than their true limit. Auction has real strengths, but neither of those risks is small.

Which selling method gets the highest price in the Perth Hills?

The one that makes the most genuine buyers compete for your specific home. In a market where many buyers need conditions, forcing unconditional bidding can thin the field, while a method that keeps those buyers in and makes them compete can capture more. But if there is only one buyer, no process invents competition, and hard negotiation is the answer. The right method follows from the property and the buyer pool.

Selling in the Perth Hills or Foothills

Bedfordale, Roleystone, Kelmscott, Mount Nasura, Mount Richon and Seville Grove are not one market. An acreage block with a workshop and a valley outlook attracts a completely different buyer to a family home on a cottage block, and the right method follows from the property, not from what the agency prefers to sell.

I will tell you straight which of the three I think suits your home, including when the answer is not ours.

Book a free Perth Hills and Foothills property appraisal⁠, and read our Best Service Guarantee⁠.

Truth. Strategy. Sold.

About the author: Brendan Leahy has been selling homes throughout the Perth Hills and Foothills since 2002, with more than 1,500 personal sales. Learn more on Brendan Leahy’s author profile

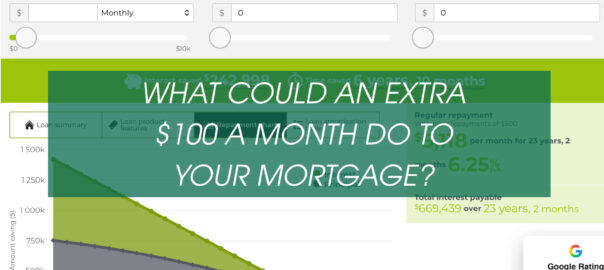
What Does an Extra $100 a Month Actually Do to Your Mortgage?

A friend sent me two courses promising to pay a home loan off faster. Here is the free version.

By Brendan Leahy, Naked Real Estate

A friend recently sent me links to a couple of courses that promised clever strategies for paying off a home loan faster. I had a look at both. I was not impressed.

Before anyone pays thousands of dollars for a strategy, I would suggest something far less exciting. Open a mortgage calculator, put your own numbers in, and see what an extra $100 a month does.

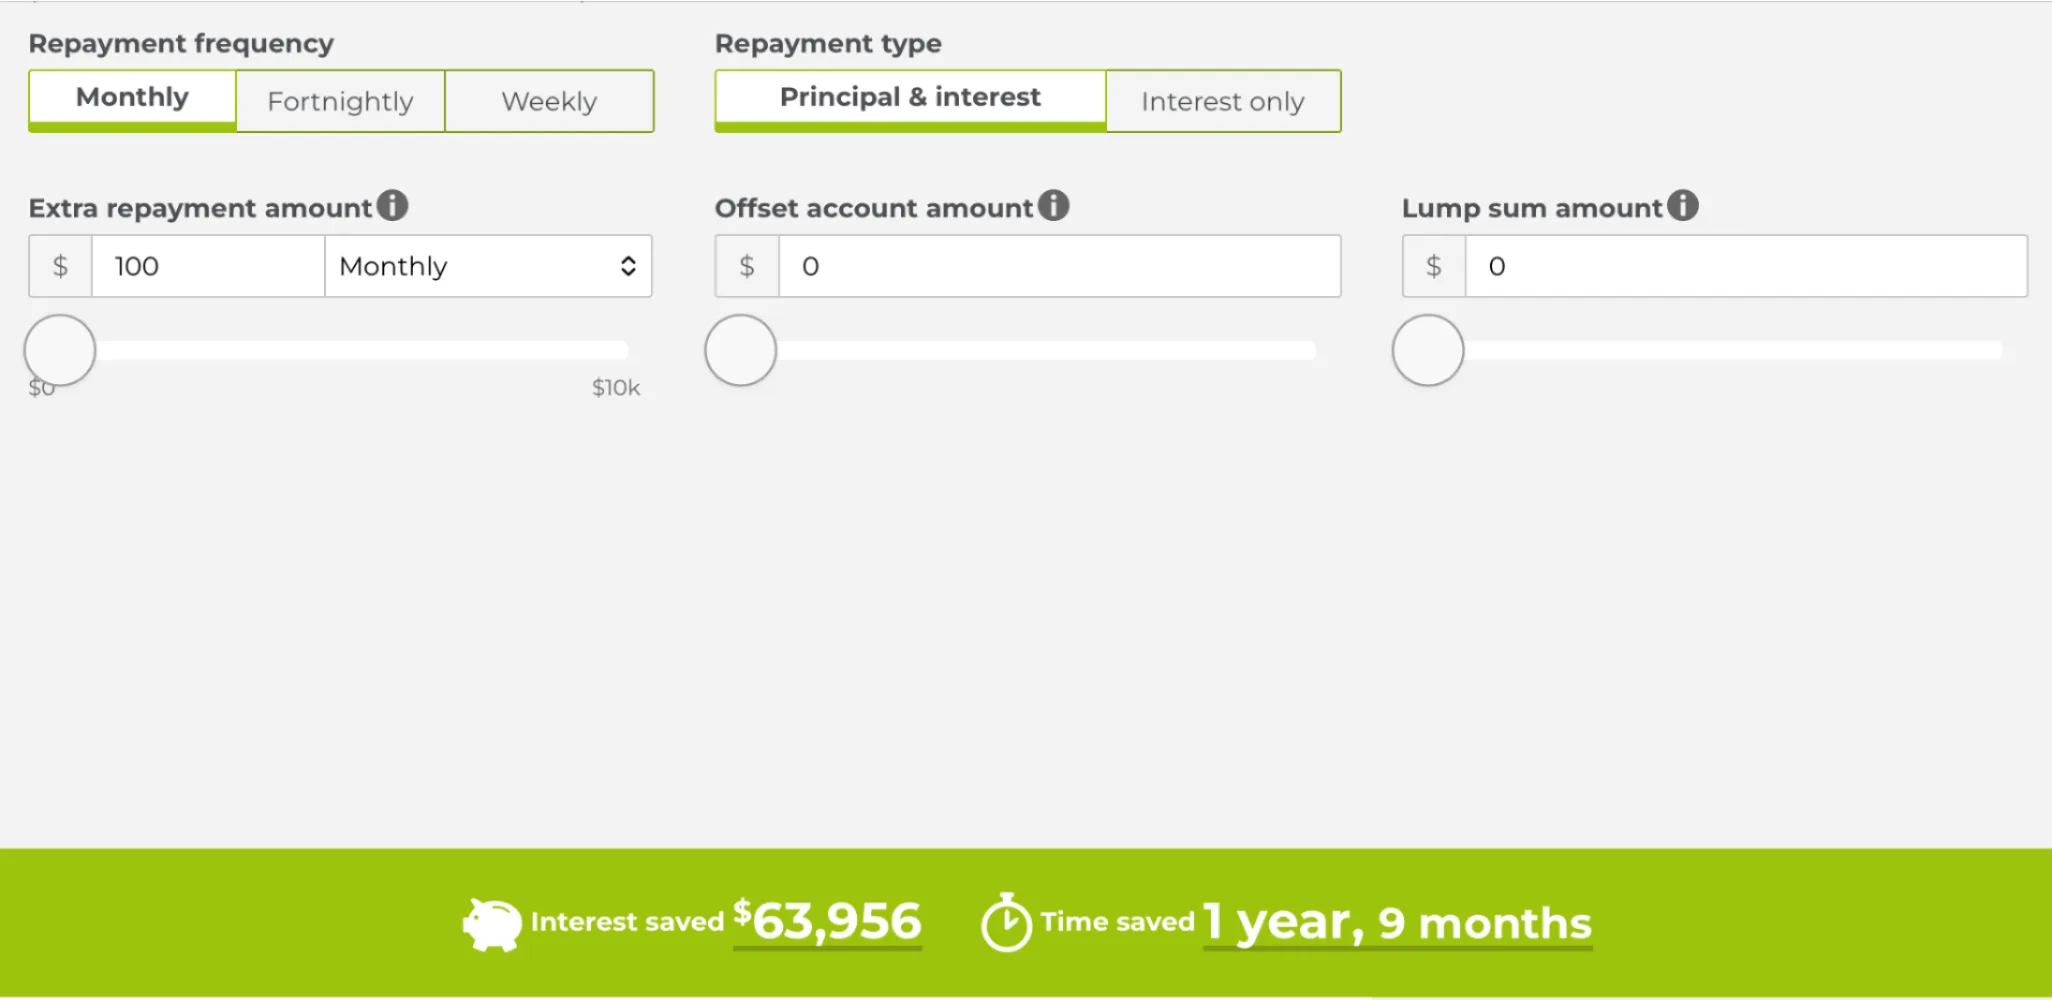
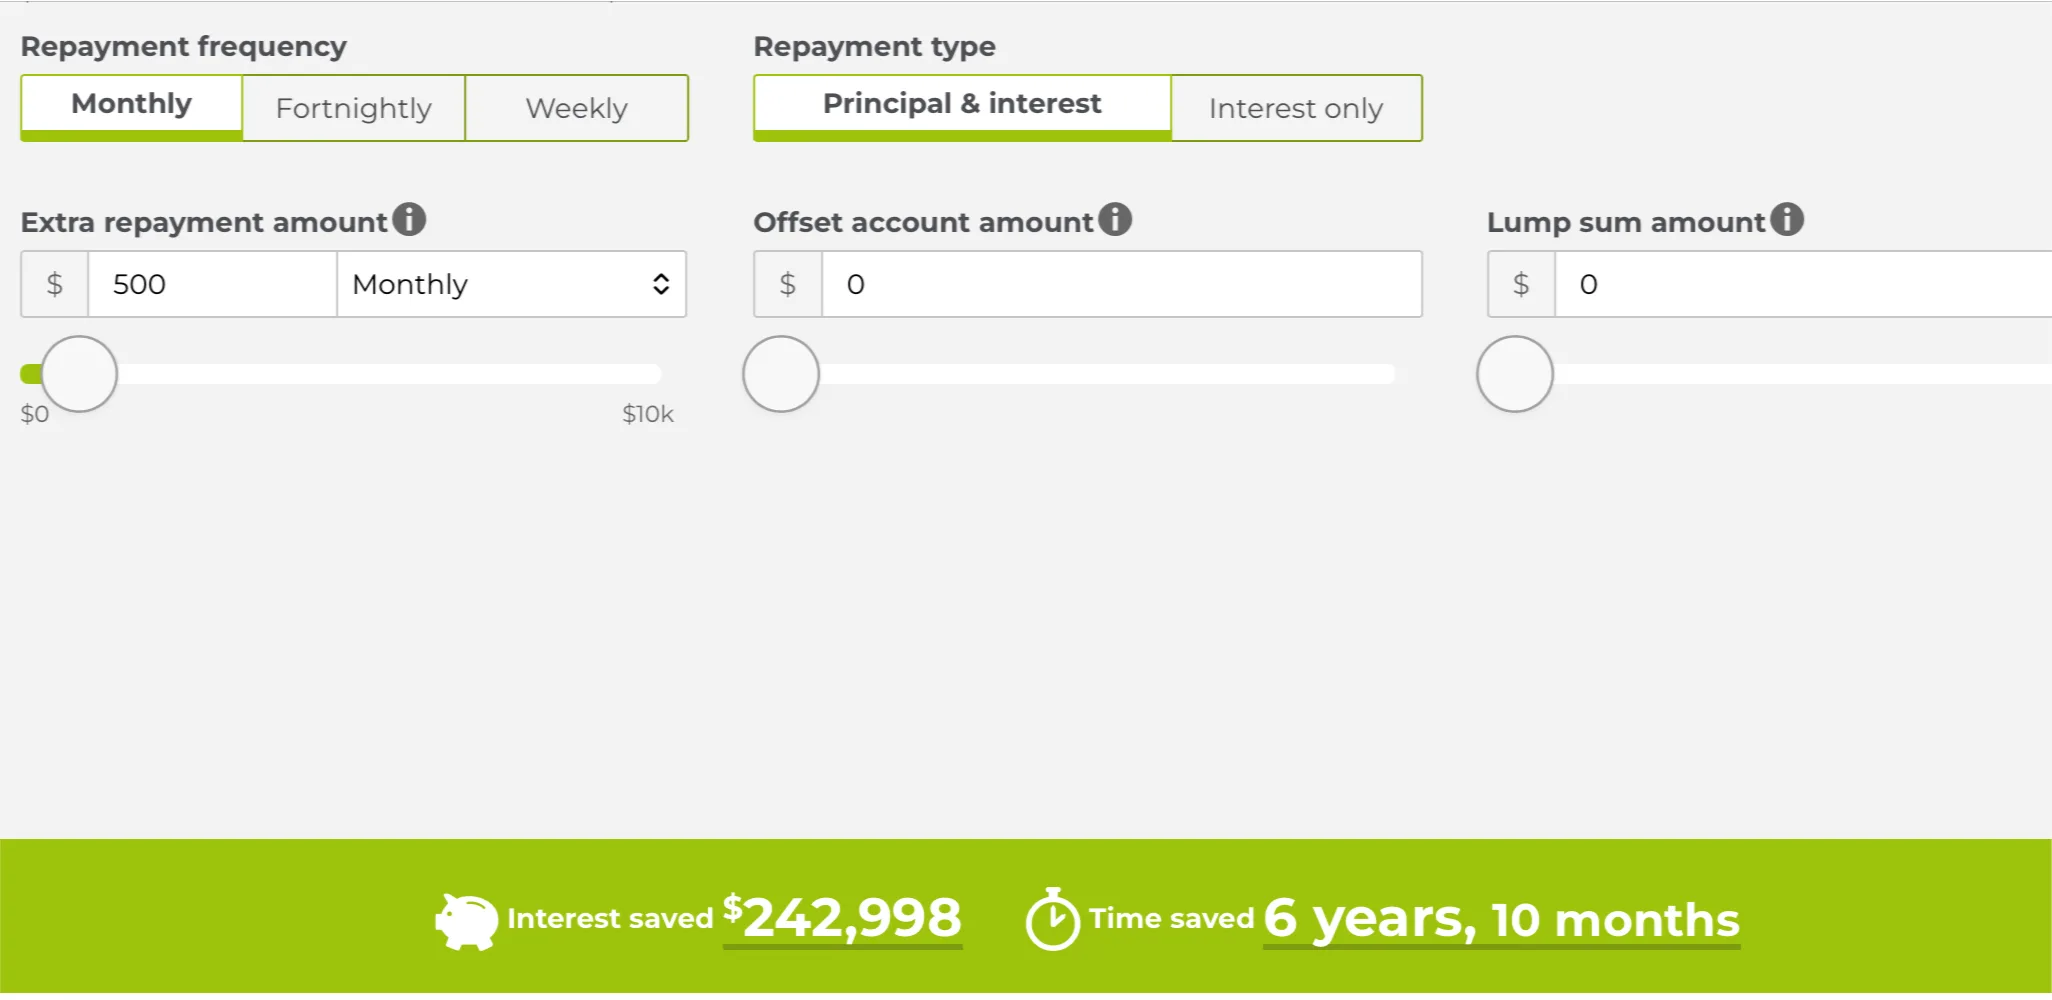
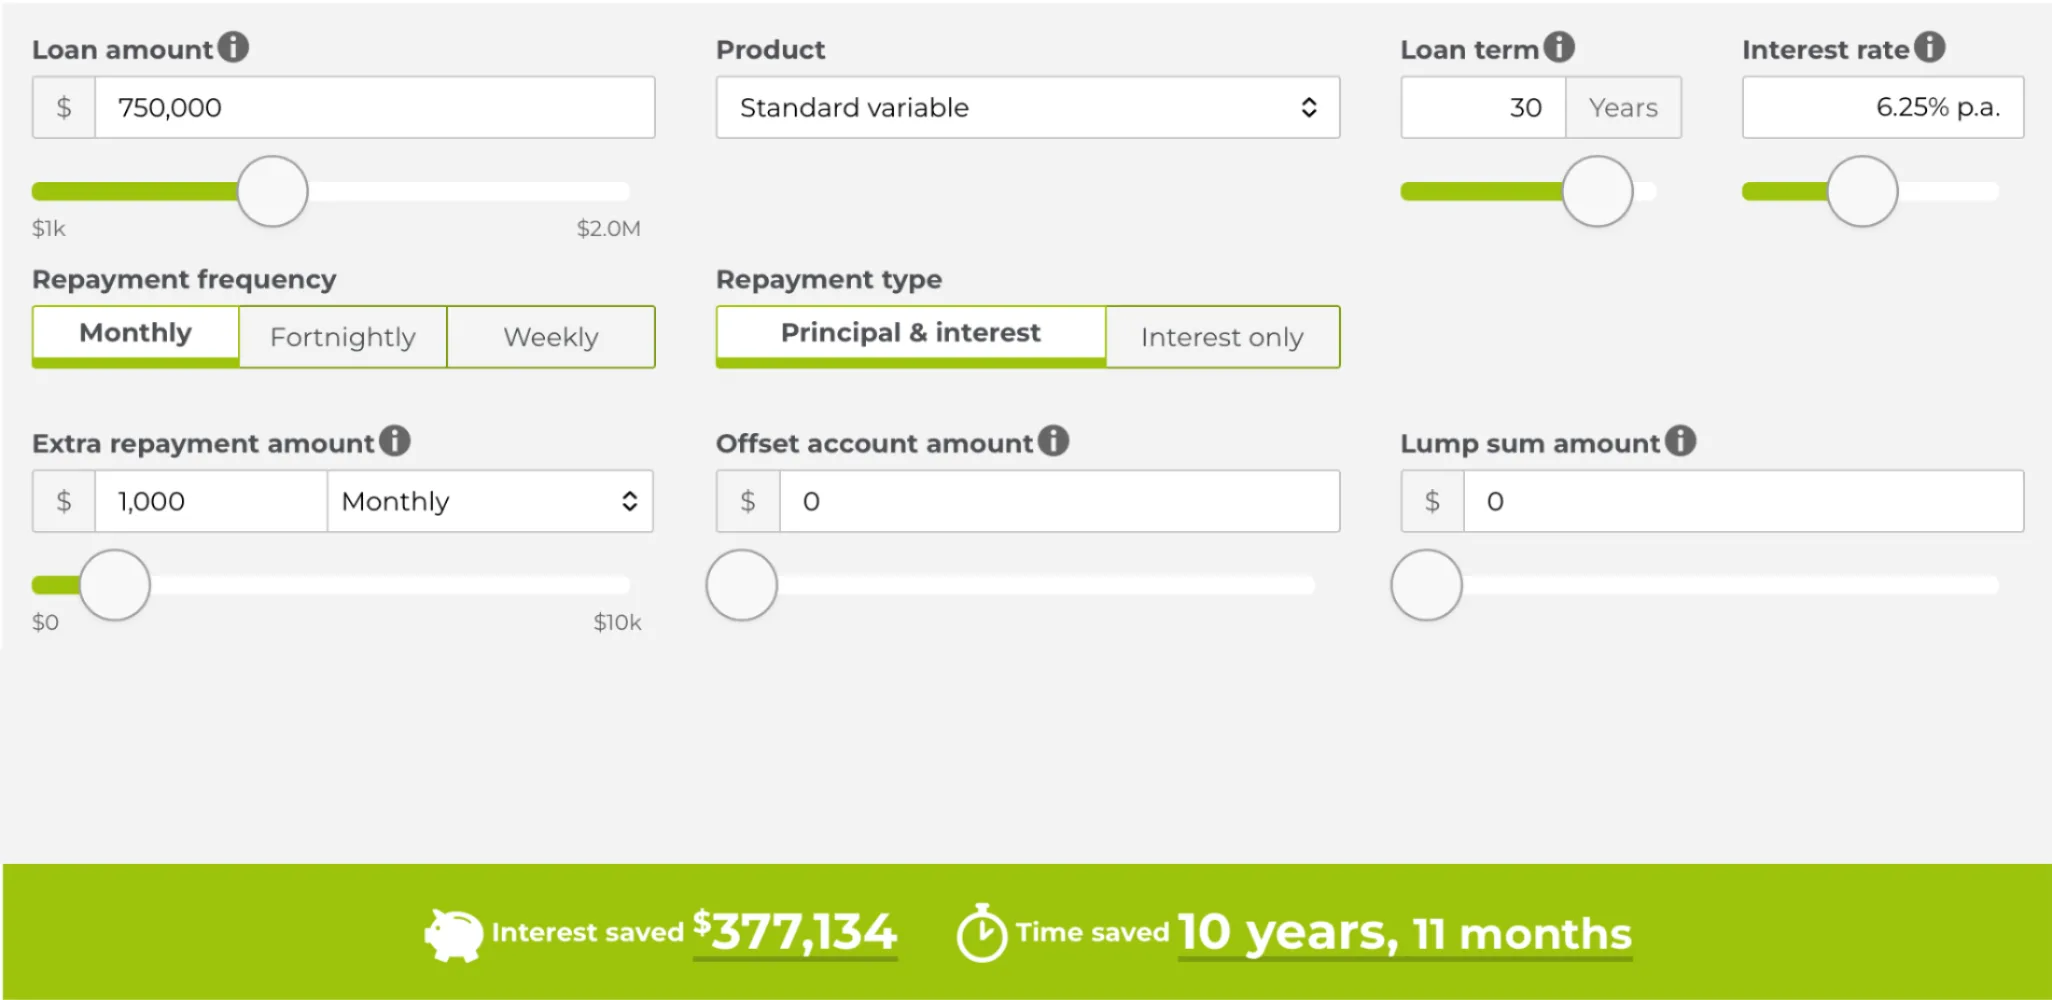
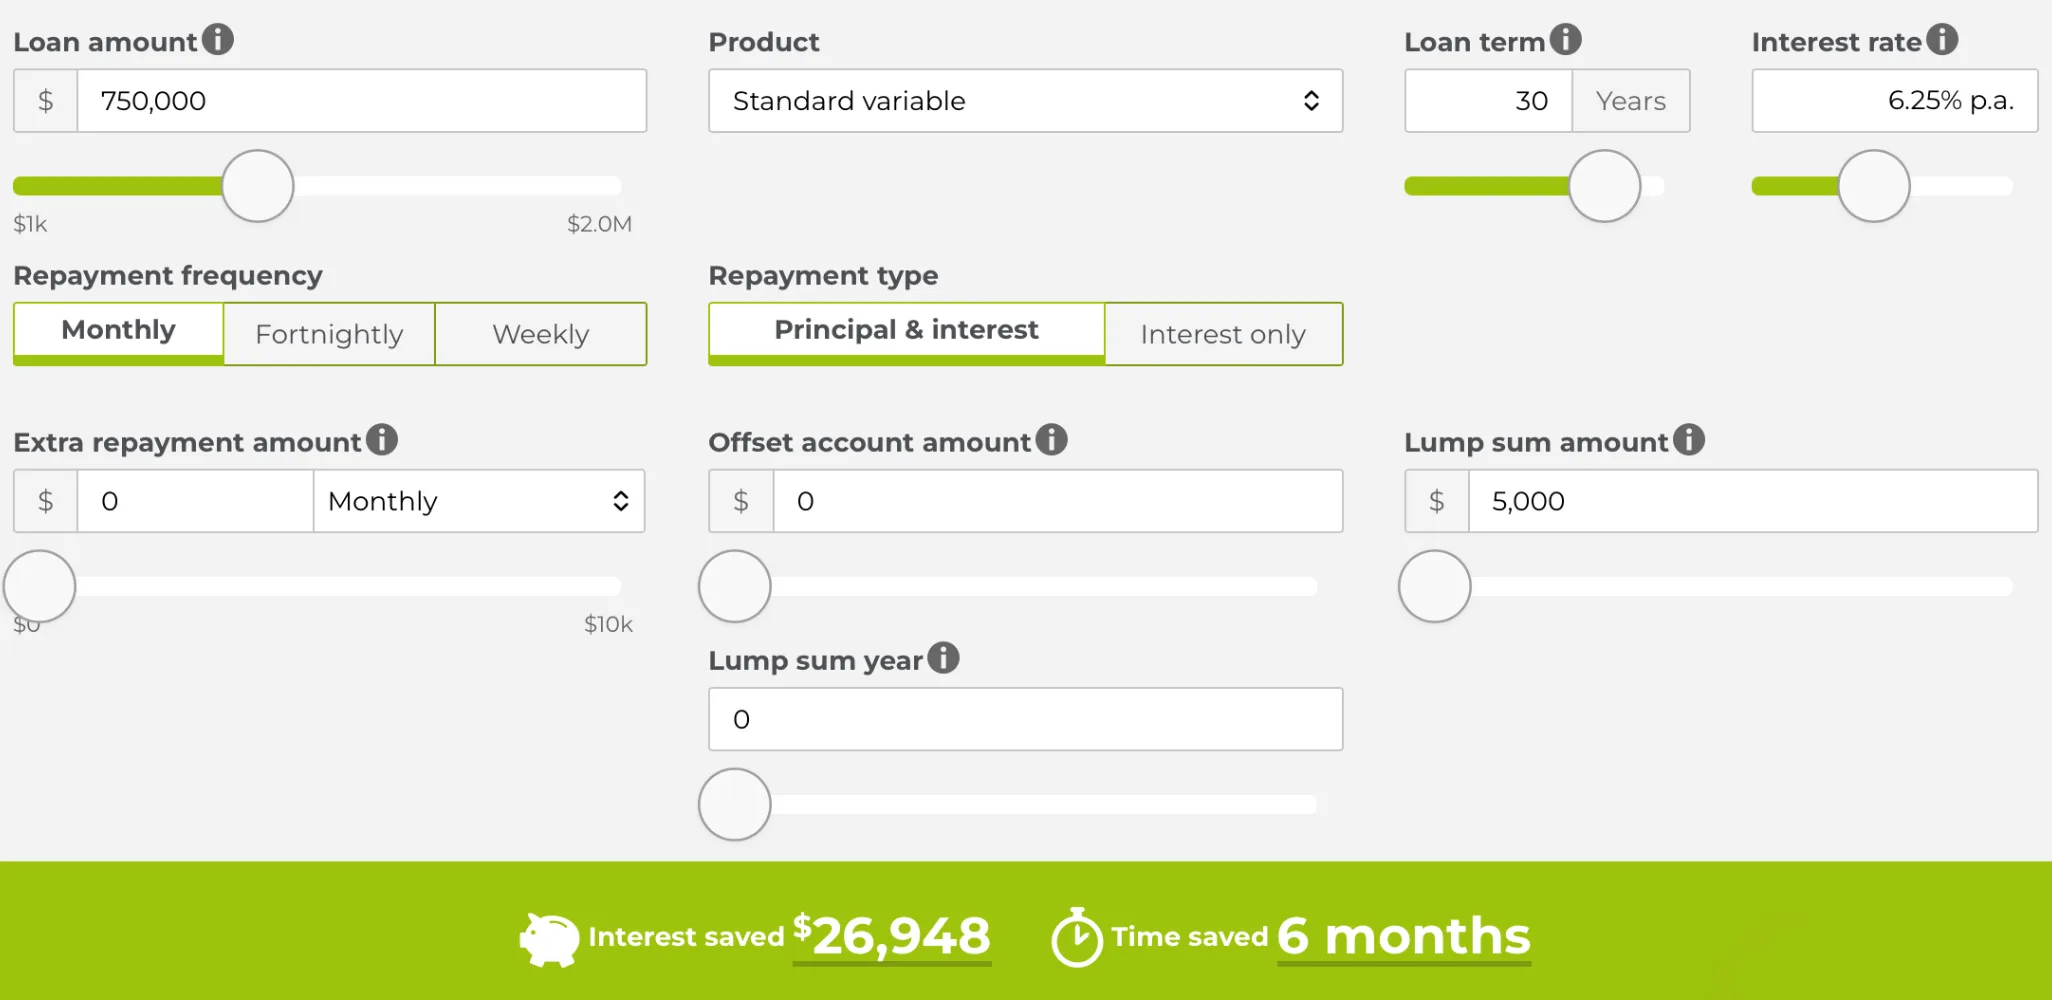
I ran it while writing this, on our own calculator, using a $750,000 loan over 30 years and an illustrative interest rate of 6.25 per cent, broadly around current owner-occupier lending rates at the time of writing.

  • An extra $100 a month saves $63,956 in interest and takes 1 year and 9 months off the loan.


  • An extra $500 a month saves $242,998 and takes off 6 years and 10 months.

  • An extra $1,000 a month saves $377,134 and takes off 10 years and 11 months.

  • And a single $5,000 lump sum, paid at the start, saves $26,948 and takes off 6 months.

No course. No strategy. No fee.

This article is general information only. It is not financial, tax or credit advice. Mortgage products, interest calculations, fees, redraw rules and offset arrangements differ between lenders. Speak with your lender, mortgage broker, accountant or a licensed financial adviser about your own circumstances.

Try our Mortgage Repayment Calculator

The part nobody tells you: timing beats size 

Look closely at those four numbers, because the most useful thing in them is not the biggest figure. 

Work out what each one costs you, and what it takes off the interest. 

The $100 a month adds up to roughly $33,900 of your own money over the life of that loan. It removes $63,956 of interest. 

The $500 a month adds up to about $139,000. It removes $242,998. 

The $1,000 a month adds up to about $229,000. It removes $377,134. The $5,000 lump sum costs you $5,000. It removes $26,948. 

Put those side by side and the pattern is not really about size. The lump sum is a small fraction of what the monthly options cost, and it still takes a meaningful amount of interest off, because every dollar of it is working for the full thirty years. A dollar you pay in year twenty-two only gets to work for eight. 

That is the actual principle, and it is worth more than any strategy anyone will sell you. It is not how much you pay. It is how early it lands. 

Two things follow from that. 

If a lump sum ever comes your way, putting it on early does disproportionate work. And if you can only manage a small amount each month, start now rather than waiting until you can afford a bigger one. Most families cannot magic up $1,000 a month, and the way this 

topic usually gets discussed makes them feel there is no point starting at all. There is very much a point. 

One caveat on the lump sum figure. That $5,000 is modelled as landing at the start of the loan. The same $5,000 ten years in saves considerably less, for exactly the reason above. 

Why it works 

A principal and interest home loan has two parts. Some of your repayment reduces what you borrowed. The rest is interest charged on what you still owe. 

In the early years of a long loan, a large share of each repayment goes to interest. Reduce the principal sooner and there is simply less balance left for future interest to be calculated on. 

ASIC’s Moneysmart makes the same point: extra repayments can help pay a mortgage off sooner and reduce total interest, particularly when made earlier in the life of the loan. 

I describe it in plain English as compounding in reverse. That is not the technical term, but it is the right idea. Compounding is what makes banks money. Extra repayments turn a little of it back the other way. 

What we did when we bought our first home 

When I bought my first home, we had no strategy at all. We were just determined to get ahead where we could. 

We would do the weekly shopping, and on the way out we would pass the bank. If there was $5 or $10 or $50 left in the wallet, we would walk in and put it on the loan. 

It did not feel like much. Some weeks it was a few dollars. 

But the logic was simple. If that money came off the principal today, I was not paying interest on it for the next twenty or thirty years. 

One small payment changes nothing. A lot of small payments, made consistently over many years, change quite a lot. 

You do not have to stop living 

This is where mortgage advice gets ridiculous. Someone tells a family to cancel everything they enjoy and live on baked beans until the loan is gone. 

That is not what I am suggesting. Life still has to be lived. 

But it is worth sitting down once or twice a year and looking honestly at where the money goes. Streaming services. App subscriptions. A gym membership nobody uses. Delivery fees. A storage plan signed up for years ago and forgotten. 

Individually none of it looks dramatic. Together it sometimes adds up. 

Maybe you find $50. Maybe $150. Maybe there is genuinely nothing spare, and that is a perfectly fine answer. 

The point is to make the choice consciously. If an extra $100 this month gives your family more value than putting it on the mortgage, spend it and enjoy it. Just put the $100 into the calculator once so you know what you are choosing between. 

Lump sums count too 

Extra repayments do not have to be monthly. A tax refund, a bonus, a commission payment or money from selling something can go straight onto the principal and reduce the balance immediately. 

Moneysmart specifically identifies bonuses and tax refunds as lump sums that can help reduce a loan faster. 

This is where the timing point really earns its keep. On the example loan, a single $5,000 tax refund put straight onto the principal early saves $26,948 in interest and six months off the term. That is one refund, put on once, taking nearly $27,000 of future interest off the loan. 

Our calculator has a lump sum field and a lump sum year field, so you can see what the same amount does at different points in the loan. The difference is worth looking at. 

Offset, redraw and extra repayments are three different things

These get used interchangeably and they are not the same. 

An offset account is a transaction account linked to your loan. If you owe $500,000 and have $20,000 in a 100 per cent offset, interest is generally calculated as though you owed $480,000. The money stays accessible. 

That flexibility is genuinely useful, but offsets are not automatically better. Some loans with offset facilities carry higher rates, package fees or account fees, and some offer only a partial offset rather than 100 per cent. The benefit has to be weighed against the cost of the product. 

A redraw facility generally lets you take back extra repayments you have already made. The rules vary widely between lenders, and there can be limits, minimums, fees or delays. Moneysmart recommends checking your lender’s actual terms before relying on redraw for access to cash. 

That distinction matters if your household also needs an emergency buffer. Paying every spare dollar into the loan is not always the right call if getting it back out is difficult. 

Extra repayments simply reduce the principal. 

The calculator lets you model an offset balance as well, so you can compare the two before you talk to a broker about which structure suits you. 

Fortnightly repayments 

One common approach is paying half the monthly amount every two weeks. Because there are 26 fortnights in a year, that can work out as the equivalent of 13 monthly repayments instead of 12, depending on how your lender structures it. 

Moneysmart lists this as one way to get ahead, but how your particular lender calculates and applies repayments matters. Check before assuming. 

Our calculator lets you switch between monthly, fortnightly and weekly.

Before you buy an investment property because someone told you it is a tax strategy 

This is where I get most cautious about courses marketed online. 

There is nothing wrong with owning an investment property. A well chosen one can be part of a sensible long term plan. 

But buying a property mainly because of tax benefits is a different thing, and the rules have just changed significantly. 

The reforms announced in the 12 May 2026 Federal Budget are now law, and the detail below reflects the position as at August 2026. From 1 July 2027, negative gearing on residential property is generally limited to new builds. Properties held at 7:30pm AEST on 12 May 2026 are exempt from the changes. For established residential property acquired after that time, losses will generally no longer be deductible against unrelated income such as wages, though they can be applied against residential property income and carried forward. 

From 1 July 2027, the existing 50 per cent CGT discount is being replaced for many future gains with inflation-based cost base indexation, together with a minimum 30 per cent tax rate on relevant real capital gains. There are exceptions and transitional rules, including special treatment for new residential builds and the existing main residence exemption. The changes apply broadly across CGT assets, not only property. 

Two things worth being very clear about. 

Your own home is not affected by the CGT change. The main residence exemption is unchanged. If you are reading this as a homeowner rather than an investor, none of the above applies to the house you live in. 

Capital growth and tax treatment are different things. Property values will do whatever the market does. What has changed is how gains and losses are taxed, not whether property can grow in value. Anyone telling you either that property is now worthless or that it is still a guaranteed tax play is overselling. 

If somebody is recommending you take on hundreds of thousands of dollars of debt because of tax benefits, talk to a qualified accountant or financial adviser who knows your actual circumstances. Not someone selling a weekend course. 

The boring version usually wins 

There is something appealing about a clever strategy. It feels like a shortcut everyone else missed.

But on a home loan, the boring approach is genuinely powerful. Spend less than you earn where you reasonably can. Keep an emergency buffer. Pay on time. Put extra against the loan when it suits. Review your rate regularly, because Moneysmart notes that even a slightly lower rate can save substantial money over a long term. Repeat. 

Nobody could sell a seminar on that. It still works. 

You cannot control the Reserve Bank, or your lender’s variable rate, or what property prices do next year. You can have some influence over how much you borrow, how much you repay, how often, how much sits in an offset, and whether you review your loan. Those decisions compound in your favour over a long period. 

Have a play with your own numbers 

The figures above are for one example loan. Yours will be different. 

Put in your real balance, your rate and your remaining term. Then try $50, $100, $500. Try a lump sum. Try an offset balance. Switch to fortnightly. 

Then look at the only two numbers that matter: interest saved, and time saved. 

You might decide extra repayments are not realistic right now. That is a completely legitimate answer, and it is a better answer for having seen the numbers.

Try our Mortgage Repayment Calculator

Frequently asked questions 

Do extra repayments really reduce the interest on a mortgage? 

Yes. On a principal and interest loan, interest is charged on what you still owe, so reducing the principal sooner leaves less balance for future interest to be calculated on. The effect is larger the earlier in the loan the repayment is made. On the example loan, an extra $100 a month removes nearly $64,000 of interest. 

Is it better to make a lump sum early or spread extra repayments out? 

Timing matters more than size. A dollar paid early works for the whole remaining term, while a dollar paid near the end works only briefly. That is why a single lump sum paid early can take off a surprising amount, and why starting small now beats waiting until you can afford more. 

Is an offset account better than making extra repayments?

It depends on the product. An offset reduces the interest calculated on your loan while keeping the money accessible, which is useful if you also need an emergency buffer. But some offset loans carry higher rates or fees, and some are only partial offsets, so the benefit has to be weighed against the cost. Get advice on your own situation. 

Do fortnightly repayments help pay off a home loan faster? 

They can. Paying half the monthly amount every fortnight can work out as 13 monthly repayments a year instead of 12, depending on how your lender applies it. Check how your particular lender calculates repayments before assuming. 

Does the change to capital gains tax affect my own home? 

No. The main residence exemption is not affected by the changes. The reforms are aimed at investment assets. If you are reading this as a homeowner rather than an investor, they do not apply to the house you live in. 

The bottom line 

You do not need a course to understand one of the simplest ways to reduce the cost of a mortgage. Reduce the principal sooner and there is less balance for interest to be charged on. 

For some households that might be an extra $1,000 a month. For most it is closer to $100. Some months it will be nothing at all, and that is life. 

But an extra $100 a month on that example loan is $63,956 that stays in your pocket instead of going to your lender, and nearly two years of your life back. One $5,000 refund put on early is nearly $27,000. 

When we bought our first home, sometimes all we had left after the shopping was a few dollars. We put it on the loan anyway. It was not glamorous and nobody could sell a course around it. 

Every dollar we paid off belonged to us instead of the bank. I would much rather see that money in your pocket. 

Truth. Strategy. Sold. 

About the author: Brendan Leahy has been selling homes throughout the Perth Hills and Foothills since 2002, with more than 1,500 personal sales.

This article provides general information only and does not constitute financial, tax, credit or investment advice. Calculator results are estimates based on the information entered and the assumptions used. Interest rates, fees, loan features and repayment calculations vary between lenders and change over time. Before changing your loan, making an investment decision or relying on any tax treatment, speak with an appropriately qualified professional. 

Can a Buyer or Seller Back Out of a Property Contract in WA?

By Brendan Leahy, Naked Real Estate 

You have signed the contract. Finance is sorted. Settlement is a few weeks away. Then something changes. A buyer decides the move no longer feels right. A seller has second thoughts about leaving the family home. A bank is running late. 

Here is the short version. Changing your mind is not, by itself, a legal reason to end a property contract in Western Australia. 

Once an Offer and Acceptance has been signed and acceptance communicated, it is generally a binding contract. There is no automatic cooling-off period for an ordinary residential contract in WA unless the buyer and seller have specifically negotiated one into the contract themselves. If the contract contains a condition that has not been satisfied, that is a different conversation. But where the contract is unconditional, or every condition has been met, neither side can simply announce a change of heart and walk away without financial and legal consequences. 

This article is general information only and is not legal advice. There are a lot of variables, and the special conditions written into your particular contract can change the outcome completely. 

What this guide covers 

Read this first: your special conditions matter more than this article 

Everything here is drawn from the standard forms used in Western Australia: the Offer and Acceptance, and the Joint Form of General Conditions that sits behind it. 

But those General Conditions apply to your contract only so far as they are not varied by or inconsistent with the conditions and special conditions of your particular contract. Where there is a conflict, your contract wins. The standard conditions say this themselves: where a provision of the individual contract is inconsistent with them, the individual contract takes priority to the extent necessary to remove that inconsistency. 

That is not a technicality. It is the single biggest reason two people can read the same article and get different answers. A special condition can extend a date, change a notice period, add an obligation, remove a right, or create a termination right that does not exist in the standard form at all. Annexures do the same. So use this guide to understand how the system works and what questions to ask. Do not use it to diagnose your own contract. Read your contract, and get your own legal advice on it. 

The three situations, and why they are not the same 

Almost every “can I get out of it” conversation is really one of three situations, and the rules are different for each. 

One, a delay, where both parties still intend to complete. A slow bank, a mortgage discharge that has not come through, documents not returned. This is a money question, not a survival question. 

Two, a finance condition that has not been resolved. The finance date has passed and no notice has been given either way. This works differently to everything else in the contract, and it catches more people out than anything else. 

Three, a refusal to complete. One party has decided they are not going ahead. This is where default notices, termination, forfeiture and resale come in, and where the numbers stop being predictable. 

The contract treats these three separately. So should you, and so should anyone advising

you. The rest of this guide summarises each, and links to a full article on each one. 

Situation one: settlement is delayed 

Settlement is due on the agreed date, and time is of the essence. If settlement is not completed within three business days after the settlement date for a reason not attributable to the seller, the buyer must pay the seller interest on the balance and any other money payable at settlement. If the delay is attributable to the seller, the seller allows the buyer compensation on the same basis. Those are deliberately different tests, so a buyer can end up paying interest for a delay that was nobody’s fault in particular, or caused by their own bank. 

The prescribed rate under the 2022 General Conditions is 9 per cent per annum calculated daily, not 9 per cent per day. On a $1.15m balance that is about $284 a day, so a two-week delay is roughly $3,970. Importantly, where the sale still completes, that interest is generally the whole claim for the delay, not the start of a list, so a frustrated party usually cannot stack removalist and accommodation costs on top. 

A delay is about money, not about the contract ending. Nothing in the delay provisions cancels the contract. 

Read the full guide: What happens when settlement is delayed in WA for the exact process, the “ready, willing and able” rule, how electronic settlement changes things, and the worked numbers. 

Situation two: the finance clause is an obligation, not a safety net 

A lot of buyers treat a finance condition as a way out. It is not. Under the current Offer and Acceptance, the buyer must apply for finance immediately after the contract date, use all best endeavours in good faith to obtain approval, and immediately tell the seller whether finance was approved or rejected. 

Here is the trap. If the buyer does not apply as required, does not use best endeavours in good faith, or does not give notice once approval comes through, the contract does not end under the finance clause and the buyer cannot terminate under it either. The seller’s rights are not affected. A buyer who sits on their hands does not get released. They lose the protection of the clause and stay bound, while the seller keeps every right. And if neither an approval nor a non-approval notice has been given once the finance date passes, the contract stays in full force, and the seller can terminate in writing at any time while that continues.

Read the full guide: The finance-clause trap that catches WA buyers out for what counts as approval, why some conditional approvals are not “finance approval” under the contract, the seller’s right to check on your application, and what to do at each deadline. 

Situation three: someone refuses to complete 

A delay is one thing. A refusal is another, and it moves out of the interest provisions into default and termination, where the money stops being calculable. 

Nothing happens automatically. A contract does not die on its own because someone misses a date. Neither party may terminate for the other’s default, and a seller may not forfeit a deposit or retake possession, unless a Default Notice has been given and the default not remedied within the time required, generally ten business days. The one exception is repudiation, where a party makes clear they do not intend to be bound. And a Default Notice only supports termination if it states that the contract may be terminated if the default is not remedied, a trap that catches sellers who draft their own. 

After a valid termination, the seller’s rights sit alongside each other, not as alternatives: forfeit the deposit (only up to 10 per cent of the price), sue for damages, and resell. If the property is resold within twelve months, a liquidated-damages mechanism can require the original buyer to pay the shortfall. Walking away from a large contract can create a liability many times the size of the deposit. 

Read the full guide: What happens when a buyer or seller refuses to complete in WA for the default process, specific performance explained properly, the seller’s and buyer’s options, and the resale arithmetic worked through. 

The fight over the deposit, and how it is supposed to work 

When a contract falls over, the argument almost always lands on the deposit, and there is a specific process almost nobody knows exists. 

The deposit is held by the deposit holder as a stakeholder. It is not the seller’s money and not the buyer’s until the position is resolved. If a party says the contract is terminated and they are entitled to the deposit, they serve notice on both the deposit holder and the other 

party. The other party then has five business days to serve a notice disputing it. If no dispute notice arrives, the deposit holder pays the claimant after eight business days. If a dispute notice does arrive, the deposit holder can obtain legal advice, start interpleader proceedings, and deduct those legal costs from the deposit itself. That last part deserves emphasis: fighting over a deposit can shrink the deposit. 

I had a matter where a buyer’s finance was declined and the deposit fell to be dealt with. The seller had been reading material online and instructed us not to release it. The deposit

was $10,000. It escalated, the buyer engaged a solicitor, I checked with my own solicitor to be sure we had not missed anything, and the seller’s position was wrong. Once the seller finally got proper advice, the deposit was released to the buyer and the seller paid about $8,500 towards the buyer’s legal costs. A dispute over releasing $10,000 ended with the buyer getting the $10,000 anyway and the seller roughly $8,500 worse off. The problem was not that the internet exists. It was using general or outdated information to override the current contract, and getting advice only after the cost had been incurred. 

One more point. If a buyer does not pay the deposit at all, or pays by a cheque that is dishonoured, that sits outside the usual default process. The seller can give notice requiring payment within 48 hours, and if that is not met the buyer is in default and the seller may terminate. That is a much shorter runway than the ten-business-day default process. 

Can both sides just agree to cancel? 

Yes, sometimes, and this is the exit people usually should be asking about and rarely do. A binding contract can be ended by properly documented mutual agreement. If a buyer’s circumstances have genuinely changed, they can ask, and the seller may agree to release them on terms, which might include the seller retaining all or part of the deposit, a contribution to costs, an agreed release date, and each party releasing the other from future claims. 

Three things to understand. The seller is not obliged to agree to anything; a release is a negotiation, not a right. The agreement has to be recorded properly, which is legal work, and each party should get independent advice. And the agent’s role here is to communicate, not to draft. I can carry the message and be straight with both sides about the practical position. I should not be drafting a legal release or advising either side about giving up contractual rights. That is not me being unhelpful. It is me staying in my lane so the document you end up with actually holds. 

Sometimes settling and reselling is the least damaging option 

This sounds counterintuitive. I have dealt with buyers who no longer wanted to proceed even though finance was approved and there was no right to terminate. In one case the change was driven by family circumstances. My advice was to get legal advice, complete the purchase, and put the home straight back on the market. The property resold quickly. They still carried costs, including the selling fee and the transfer duty already paid, but the resale covered a meaningful part of it, and it was finished in weeks. 

Compare that to a refusal to settle: a default notice, a termination, a resale controlled entirely by the seller, a claim for the shortfall, and legal costs, over months, with an uncertain number at the end. Nobody wants to buy a house in order to sell it, but the least

expensive way out of a binding purchase is sometimes to honour it, take ownership, and move on quickly. The duty, tax, finance and legal consequences all need working through with your lawyer and financial adviser, but it is an option worth putting on the table early, because it is often the one nobody has thought of. 

Before you sign, you are still in control 

There is an enormous difference between thinking about an offer and being bound by an accepted one. Before you sign you can take time, get advice, talk to your broker, investigate the property, adjust your conditions, or decide not to proceed at all. After the contract becomes binding, your choices narrow dramatically. 

Under the current Offer and Acceptance, acceptance is sufficiently communicated when the accepting party, their representative or the agent gives verbal or written notification that the accepting party has signed. Until that happens, there is no contract, and a buyer can withdraw their offer. I have watched sellers learn this the hard way. I once presented a cash offer of $1.5m in a difficult market, a strong offer at the time. The sellers wanted to sleep on it, which was entirely their right. By eight the next morning the buyer had withdrawn, and the property took another eighteen months to sell for the same price. There was nothing improper about it. But until acceptance is communicated, there is no deal to honour. Taking the time you need to make a clear decision is sensible. Assuming the offer will still be there tomorrow is not. 

What to do if you think you cannot settle 

Act immediately. Do not wait for settlement day and do not go quiet. Almost every bad outcome I have seen was made worse by delay and silence. 

If you are the buyer: contact your settlement agent today, contact your lender or broker, tell the agent what is happening, get independent legal advice, work out honestly whether this is a temporary problem or a refusal to complete because they are treated very differently, and ask your lawyer about the realistic options, including an extension, a mutual release, or settling and reselling. 

If you are the seller: contact your settlement agent today, start or chase the mortgage discharge, tell your selling agent, get legal advice before refusing access, withholding documents, refusing to release a deposit or issuing any notice, do not assume you can keep the deposit or terminate without following the contract, and keep written records of every instruction and notice. 

The earlier a problem is raised, the more options remain. That is the whole game.

One carve-out worth knowing 

Everything above is written for an ordinary residential sale of a freehold property. If you are buying a strata lot, a proposed strata lot, or an off-the-plan property, there are separate rights to terminate that come from the strata legislation rather than the contract, and they sit alongside your contractual rights. The general picture here is still useful, but do not assume the answer is the same. Ask your settlement agent or lawyer specifically about the strata position. 

Frequently asked questions 

Can a buyer change their mind after signing an Offer and Acceptance in WA? 

Not merely because they have changed their mind. There is no automatic cooling-off period for an ordinary residential contract in WA. A buyer may have a right to terminate under the finance clause, a special condition, an annexure or another legal right, but they should get advice before acting on any of them. 

Can a seller change their mind after accepting an offer? 

Generally not, where a binding contract has been formed and the buyer is complying with it. A seller who refuses to complete may face a claim for damages or an order compelling the sale to proceed. 

Does a WA contract end automatically if settlement is three business days late? 

No. The three-business-day period relates to interest and compensation, not to the contract ending. Termination generally requires the default-notice process, unless there has been repudiation or another specific right applies. 

Is the late-settlement rate 9 per cent per day? 

No. Under the 2022 General Conditions the prescribed rate is 9 per cent per annum, calculated daily. 

If the buyer defaults, does the seller automatically keep the deposit? 

No. The seller has to follow the contract, which generally means a valid default notice and a valid termination before the deposit can be forfeited. Repudiation is treated differently. 

Does the finance condition end the contract automatically when the date passes?

No. If neither an approval nor a non-approval notice has been given, the contract remains in full force until the seller terminates in writing or the buyer gives a valid non-approval notice. The seller can terminate at any time while that situation continues. 

Can the buyer and seller agree to cancel? 

Yes. They can enter a written mutual release on agreed terms. Neither side is obliged to agree, and each should get advice before giving up contractual rights. 

Do the special conditions in my contract change any of this? 

They can, completely. The General Conditions apply only so far as they are not varied by or inconsistent with your contract’s own conditions and special conditions, and your contract takes priority where there is a conflict. Read your contract and get advice on it. 

The bottom line 

Western Australia’s Offer and Acceptance system is designed to create a clear, enforceable agreement, and that certainty is genuinely valuable. A buyer can plan their life around the home they have bought, and a seller can make decisions knowing the property is sold. But certainty cuts both ways, so neither side should sign casually. 

Before you sign, ask your questions, take advice, and make sure your finance and settlement arrangements are realistic rather than hopeful. After acceptance has been communicated, changing your mind is not an exit strategy. And if a settlement problem appears, get independent legal advice straight away. In this area the cost of advice is almost always smaller than the cost of finding out late. 

After more than 1,500 personal sales, my advice comes down to one line. If in doubt, do not sign until you understand the contract. Once you sign and it becomes binding, expect to honour it. 

Truth. Strategy. Sold. 

If you would like a free appraisal for your property, please enquire via the form on our ‘Book a Free Appraisal‘ page.

About the author: Brendan Leahy has been selling homes throughout the Perth Hills and Foothills since 2002, with more than 1,500 personal sales. 

This article provides general information only and is not legal advice. Every contract and every default is different, and the special conditions and annexures in your own contract can change the outcome entirely. If settlement may be delayed, if a party wants to withdraw, or if a default notice is being considered, get advice from a property lawyer immediately.

What Happens When Settlement Is Delayed in WA?

By Brendan Leahy, Naked Real Estate 

Most settlement delays are not dramas. A bank is slow, a mortgage discharge has not come through, documents have not been returned, or the electronic workspace is not ready. Both sides still intend to complete. This is a money question, not a survival question, and it is worth understanding before you panic, because the rules are more specific, and less symmetrical, than most people assume. 

This is one part of a bigger picture. For how delay fits alongside the finance clause and an outright refusal to complete, see the full guide, can a buyer or seller back out of a WA contract

General information only, not legal advice. Your special conditions can change the outcome, so read your contract and get advice on it. 

Time is of the essence, but the clock has a specific shape 

Settlement is due on the agreed date, and time is of the essence under the contract. But the interest mechanism does not bite the instant settlement is a day late. It activates only if settlement remains incomplete more than three business days after the settlement date. Termination is a separate process again, and a delay on its own does not cancel anything. 

The rule is not symmetrical, and buyers should know it 

Most people assume whoever caused the delay pays. That is not what the standard conditions say. 

If settlement is not completed within three business days after the settlement date for any reason not attributable to the seller, the buyer must pay the seller interest on the balance of the purchase price and any other money payable at settlement. If the delay is attributable to the seller, the seller allows the buyer compensation on the same basis, as a deduction from the purchase price. 

Those are different tests, deliberately. A buyer can end up paying interest for a delay that was nobody’s fault in particular, or that was caused by their own bank or settlement agent. The seller only pays where the delay is actually attributable to them. So if you are buying, that is a reason to stay on top of your lender and settlement agent, not to assume a delay

outside your control is a delay outside your wallet. 

The rate, and the panic it causes 

The prescribed rate under the 2022 General Conditions is 9 per cent per annum, calculated daily. It is not 9 per cent per day. I have seen that misunderstanding cause genuine panic. 

Interest runs from and including the original settlement date, up to but excluding the day settlement actually occurs. So the three-business-day period is not a grace period that shifts the start date. Once the clause applies, the calculation reaches back to the settlement date. 

What it looks like in practice 

Take a sale at $1.2m with a $50,000 deposit already paid, so the balance is $1,150,000. At 9 per cent per annum, that is 1,150,000 x 9% divided by 365, about $284 a day. A fourteen day delay is therefore around $3,970. 

That figure is illustrative. Interest is calculated on the balance plus any other money payable at settlement, so the real number depends on the adjustments, and your settlement agent works out the actual figure. 

The interest is the whole claim, not the start of one 

This is where a lot of online advice goes wrong. Where settlement ultimately proceeds under the ordinary delay provisions, the interest or compensation is generally the whole contractual claim arising from that delay, not the beginning of a list. The standard conditions say the parties intend it as the best estimate of the damages caused by the delay. 

So where the sale still completes, you generally cannot stack removalist costs, temporary accommodation and inconvenience on top of the interest. The interest is the remedy. That cuts both ways: it caps what a frustrated party can chase, and it makes the delaying party’s exposure calculable rather than open-ended. The position can change if court proceedings are instituted, or if the situation has moved beyond an ordinary delay into a default, which is another reason to get advice once a delay stops looking like a delay. 

You cannot claim interest if you were not ready yourself 

The delay provisions do not reward a party who was not in a position to settle. A seller who was not ready, willing and able to complete on the settlement date is not entitled to interest until they are ready and have given the buyer notice of that fact. If that notice comes within three business days of the settlement date, interest still runs from the settlement date. If it comes later, interest runs only from the day the notice was given. The same principle applies in reverse to a buyer claiming compensation for a seller delay. This is why settlement agents need to establish what actually caused a delay rather than assuming. 

There is a process for claiming it 

A party who wants interest paid at settlement must serve a notice on the other party no later than two business days before settlement, setting out the basis of the claim and the amount, which can include a daily figure. If the other party disputes it, the disputed amount is still paid at settlement and held by a representative. If the dispute has not been resolved or taken to court within twenty business days after settlement, the money goes to the party claiming it. The key point: a dispute about interest does not stop settlement. Both parties still have to complete. 

Electronic settlement changes the picture 

Most settlements now happen electronically, and the standard conditions deal with that separately. A party is not in default where they are prevented from complying because the other party or the other party’s bank has not done something in the workspace, or where settlement fails because a system at Landgate, the Office of State Revenue, the electronic network operator or the Reserve Bank is down. And while the workspace is locked for settlement, neither party can exercise a right to terminate. So before anyone starts talking about default, the first question is usually practical: what actually happened in the workspace, and whose obligation was outstanding. 

Delay is not termination 

The three-business-day rule is about money, not about the contract ending. Nothing in the delay provisions cancels the contract. If a delay hardens into a refusal to complete, that is a different situation with its own process, covered in what happens when a buyer or seller refuses to complete. And if your delay is really a finance problem, see the finance-clause trap, because that runs by different rules again. 

Frequently asked questions 

Does a WA contract end if settlement is a few days late? 

No. Time is of the essence, but a delay triggers interest or compensation once settlement is more than three business days late, not termination. Ending the contract requires the separate default process, or repudiation. 

Who pays interest for a late settlement? 

The tests are not symmetrical. The buyer pays the seller interest for a delay not attributable to the seller, which can include the buyer’s own bank. The seller pays the buyer compensation only where the delay is attributable to the seller. 

How much is the interest? 

The prescribed rate under the 2022 General Conditions is 9 per cent per annum calculated daily, not per day. On a $1.15m balance that is roughly $284 a day. Your settlement agent calculates the actual figure on the real balance and adjustments. 

Can the other side also claim removalist or accommodation costs? 

Generally not, where the sale completes under the ordinary delay provisions. The interest is intended as the whole claim for the delay, not the start of a list. That can change if the matter moves into default or court proceedings. 

The bottom line 

A late settlement is usually a money question with a calculable answer, not the end of the contract. Know that the interest test favours the seller, that the rate is 9 per cent a year and not a day, and that a party who was not ready themselves cannot claim. Stay on top of your lender and settlement agent, return paperwork the moment it arrives, raise any problem early, and get advice as soon as a delay starts to look like something more than a delay. 

Truth. Strategy. Sold. 

If you would like a free appraisal for your property, please enquire via the form on our ‘Book a Free Appraisal‘ page.

About the author: Brendan Leahy has been selling homes throughout the Perth Hills and Foothills since 2002, with more than 1,500 personal sales. 

General information only, not legal advice. If settlement may be delayed, speak to your settlement agent and a property lawyer.

The Finance Clause Trap That Catches WA Buyers Out

By Brendan Leahy, Naked Real Estate 

A lot of buyers treat a finance condition as a safety hatch. If the loan does not come together, they assume the contract quietly dies and they walk away. That is the single most expensive misunderstanding I see, because the finance clause is not a way out. It is a set of obligations you have to actually perform, and a buyer who does not perform them can end up bound to the contract with no protection at all. 

This is one part of a bigger picture. For how the finance clause sits alongside delays and outright refusals, see the full guide, can a buyer or seller back out of a WA contract

General information only, not legal advice. Finance-clause wording is specific and can be varied by your contract, so read yours and get advice on it. 

Finance approval is an active obligation 

Under the current Offer and Acceptance, the buyer must apply for finance immediately after the contract date, and must use all best endeavours in good faith to obtain approval. The buyer must then immediately tell the seller or the seller’s agent whether finance has been approved or the application has been rejected. 

Those words carry the weight: immediately, best endeavours, in good faith. They describe things you must do, not a right you can passively rely on. 

The trap most buyers never see 

Here is the part that surprises people, and it is the most important thing in this article. If the buyer does not apply for finance as required, does not use best endeavours in good faith, or does not give the seller notice once approval comes through, then the contract does not come to an end under the finance clause, and the buyer cannot terminate under it either. The seller’s rights are not affected at all. 

Read that again. A buyer who sits on their hands does not get released. They lose the protection of the finance clause and stay bound to the contract, while the seller keeps every right they had.

Older versions of the finance clause worked differently, and a lot of outdated advice still circulates as a result. In my own experience, buyers who had a change of heart would sometimes simply let the finance date pass and treat the contract as dead. Whatever someone remembers from an earlier transaction, the current clause has to be followed as it is actually written. 

What actually happens at the latest time 

There are three possible positions once the latest time for finance arrives. 

The application has been rejected, or a non-approval notice has been given, on or before the latest time. The contract comes to an end under the finance clause without further action by either party. 

An approval notice has been given, or approval obtained. The finance condition is satisfied and the contract is in full force. 

Neither notice has been given. This is the dangerous one. The contract stays in full force and effect. It does not lapse. While neither notice has been provided after the latest time, the seller may terminate by written notice, and that right remains until an approval notice or a valid non-approval notice is given. So a buyer still chasing their lender, who has not given notice either way, is in a contract the seller can end at any moment, and may still be liable if they never properly applied. 

Finance termination does not use the default-notice process 

This distinction catches out sellers and buyers alike, and it runs opposite to the rest of the contract. Where a party terminates under the finance clause, the default and remedy provisions do not apply. There is no default notice and no ten-business-day remedy period. Termination is by written notice, the deposit and any other money paid by the buyer must be repaid, and neither party has a claim against the other, except where the buyer has breached their finance obligations. That exception is the seller’s protection: a buyer who never genuinely applied does not get a clean walk-away. 

Some conditional approvals are not “finance approval” 

When a buyer says they have approval, ask what kind. The form treats an approval as approval where it is subject only to a lender’s usual terms, or to conditions the buyer has already accepted in writing. Where approval is subject to something else, an acceptable valuation, a particular loan-to-value ratio, the sale of another property, or the buyer obtaining mortgage insurance, it counts as approval only once that condition has in fact been satisfied. A conditional approval sitting in an inbox is not automatically finance

approval under the contract. If it remains subject to an acceptable valuation, that condition ordinarily needs to be met before it meets the contractual definition. 

The seller can check on you 

The seller or the seller’s agent can ask the buyer in writing for progress on the application, and for written evidence of the application, any loan offer, any rejection, and any preliminary assessment from a broker. If the buyer does not respond within two business days, the buyer is taken to have authorised the seller or agent to obtain that information directly from the lender or broker. This is not the agent being difficult. It is a contractual right, and it exists because sellers were being left in the dark. 

Practical points that save buyers 

If no date for finance is written into the contract, the latest time defaults to 4pm on the fifteenth business day after the contract date. Do not assume you have longer than you do. 

A buyer can waive the finance clause in writing before the latest time, in which case the condition is treated as satisfied. That is a decision to take with advice, not on a hunch, because it removes your exit. 

And practically: get your payslips, bank statements, identification, tax returns and details of existing debts to your broker before you sign, not after. The clock starts at the contract date, and applying immediately and using best endeavours in good faith are things you have to actually do. 

Frequently asked questions 

Is “subject to finance” a guaranteed way out of a WA contract? 

No. It is a set of obligations. You must apply immediately, use best endeavours in good faith, and give notice of approval or rejection. Fail to do those and you lose the protection of the clause while staying bound. 

What happens if the finance date passes and no one gives notice? 

The contract stays in full force. It does not lapse. The seller can terminate in writing at any time until an approval or a valid non-approval notice is given, and the buyer may still be liable if they never properly applied. 

Is a conditional pre-approval the same as finance approval?

Not necessarily. If approval is still subject to something like an acceptable valuation, the sale of another property, or mortgage insurance, it generally counts as approval under the contract only once that condition has actually been satisfied. 

What if I decide I do not want the property, can I just let finance lapse? 

No. Letting the date pass without giving notice does not release you and can leave the seller able to terminate on their terms. If you want out, get legal advice about your actual options rather than relying on the finance clause to fail for you. 

The bottom line 

Treat the finance clause as a job, not a safety net. Apply at once, chase your lender, give notice the moment you know either way, and check whether any approval is truly unconditional under the contract. A buyer who does all of that is protected exactly as the clause intends. A buyer who sits back is the one who gets caught. If your real problem is that you no longer want the property, do not rely on finance quietly failing. That is covered in the full guide on backing out of a WA contract, and it is a conversation for your lawyer. 

Truth. Strategy. Sold. 

If you would like a free appraisal for your property, please enquire via the form on our ‘Book a Free Appraisal‘ page.

About the author: Brendan Leahy has been selling homes throughout the Perth Hills and Foothills since 2002, with more than 1,500 personal sales. 

General information only, not legal advice. Finance-clause obligations are specific. Get advice from a property lawyer on your own contract.

What Happens When a Buyer or Seller Refuses to Complete in WA?

By Brendan Leahy, Naked Real Estate 

A delay is one thing. A refusal is another. When a buyer or seller makes clear they no longer intend to honour the contract, the situation moves out of the interest provisions and into default and termination, and this is where the money stops being calculable and starts being open-ended. It is also where the most dangerous assumptions live, because almost everything people believe about “just losing the deposit” is wrong. 

This is one part of a bigger picture. For how a refusal differs from an ordinary delay or a finance problem, see the full guide, can a buyer or seller back out of a WA contract

General information only, not legal advice. Do not draft or rely on a default notice without a property lawyer. Your special conditions can change all of this. 

Nothing happens automatically 

The most common misunderstanding is that a contract dies on its own once someone misses a date. It does not. 

Neither party may terminate the contract because of the other’s default, and a seller may not forfeit money paid by the buyer or retake possession because of the buyer’s default, unless two things have happened: the non-defaulting party has given a Default Notice, and the defaulting party has failed to remedy the default within the time required by that notice. A Default Notice has to specify the default and require it to be remedied within ten business days after it is properly given, or a longer period if the notice says so. 

There is one significant exception. If a party repudiates the contract, meaning they make clear they do not intend to be bound, the Default Notice requirement does not apply. 

And there is a trap for sellers. A Default Notice only supports termination if the notice itself states that the contract may be terminated if the default is not remedied in time. A notice that leaves that out does not do the job, no matter how firmly it is worded. Do not draft one of these yourself. This is the point where a property lawyer stops being optional. 

Specific performance is not what most people think

I hear this term used incorrectly more than almost any other. Specific performance does not mean putting the property back on the market and chasing the shortfall. That is a different remedy entirely. Specific performance means asking a court to order the defaulting party to actually perform the contract: to settle, to hand over the property, or to pay the money and complete the purchase. A seller who refuses to sell may face proceedings seeking an order that the sale proceed. A buyer who refuses to buy may face proceedings seeking completion. Which remedy fits a given case is a matter for lawyers and, ultimately, a court. 

What a seller can do if the buyer defaults 

Where the buyer has failed to comply with a Default Notice, or has repudiated, the seller has a menu of options, not a single automatic outcome. The seller may affirm the contract and sue the buyer for damages; affirm and sue for specific performance, with damages in addition to or instead of it; retake possession, subject to the notice requirements; or terminate by notice to the buyer. If the seller terminates, they may then elect to forfeit the deposit, sue for damages, and resell. 

Note the word elect. These are choices with consequences, and choosing wrongly can cost a seller their position. That is a decision to make with a lawyer, not with a mate at a barbecue. 

The deposit is not a cancellation fee 

Some buyers assume the worst case is losing the deposit and walking away. That assumption is unsafe. After a valid termination, the seller may forfeit the deposit AND sue for damages AND resell. Those rights sit alongside each other. They are not alternatives. 

There is one limit worth knowing. If the deposit exceeds 10 per cent of the purchase price, the seller may forfeit only the part that does not exceed 10 per cent, and anything above that is treated differently under the contract. That matters where a contract provides for a deposit greater than 10 per cent. 

The resale mechanism 

This is what people are usually reaching for when they say “specific performance,” and it is worth understanding properly. If the seller terminates and resells, the seller does not have to give the original buyer notice of the resale, and has the discretion, acting reasonably, to determine the manner and terms of the resale. 

Where settlement of the resale happens within twelve months of termination, the standard conditions do the arithmetic. You take the resale proceeds, account for the costs and expenses of the resale and the amount of the deposit that has been forfeited, and compare

the total the seller holds against the original purchase price. If the seller holds less than the original purchase price, the original buyer must pay the difference as liquidated damages. If the seller holds more, the excess belongs to the seller. Read that second one again if you are a buyer thinking about walking away: there is no upside for you in the resale. A better result for the seller does not come back to you. 

A simple illustration 

Assume a buyer contracts to pay $1.2m, defaults, the contract is properly terminated, and the property is resold within twelve months for $1m. The original buyer may face a claim built from the shortfall against the original purchase price, the costs and expenses of the resale, legal costs relating to the termination, and other recoverable losses. The forfeited deposit is brought into that calculation, so the answer is not simply one price subtracted from the other. But the point stands: walking away from a $1.2m contract can create a liability many times the size of the deposit. 

What a buyer can do if the seller defaults 

The position is broadly mirrored, and sellers who think they can simply refuse to proceed should read it. Where the seller has failed to comply with a Default Notice or has repudiated, the buyer may affirm and sue for damages, affirm and sue for specific performance or damages, or terminate. If the buyer terminates, the deposit and any other money paid must be promptly repaid, the buyer is entitled to interest earned on the deposit, and the seller must pay interest at the prescribed rate on other money the buyer paid. Where the contract is terminated as a result of one party’s default or repudiation, the standard conditions also make the defaulting party liable for the other party’s legal costs relating to that termination. 

Sometimes settling and reselling is the least damaging option 

This sounds counterintuitive. I have dealt with buyers who no longer wanted to proceed even though finance was approved and there was no right to terminate. In one case the change was driven by family circumstances. My advice was to get legal advice, complete the purchase, and put the home straight back on the market. It resold quickly. They still carried costs, including the selling fee and the transfer duty already paid, but the resale covered a meaningful part of it, and it was over in weeks. 

Compare that to a refusal to settle: a default notice, a termination, a resale controlled entirely by the seller, a claim for the shortfall, and legal costs, over months, with an uncertain number at the end. Nobody wants to buy a house in order to sell it, but the least expensive way out of a binding purchase is sometimes to honour it, take ownership, and move on quickly. The duty, tax, finance and legal consequences need working through with

your lawyer and financial adviser, but it is an option worth raising early, because it is often the one nobody has thought of. 

If a delay or finance problem is your real situation 

Not every stalled settlement is a refusal. If both sides still intend to complete and a bank is simply slow, that is a delay, and it is handled differently. See what happens when settlement is delayed. If the sticking point is a loan that has not come together, see the finance-clause trap, because that runs by its own rules and can leave a buyer bound in ways the default process does not. 

Frequently asked questions 

If I refuse to settle, do I just lose my deposit? 

No. That assumption is unsafe. After a valid termination the seller can forfeit the deposit and sue for damages and resell, and if the resale within twelve months produces a shortfall you can be pursued for the difference. Walking away can cost far more than the deposit. 

Does the contract end automatically if someone refuses to complete? 

No. Ending it generally requires a valid Default Notice that states the contract may be terminated, and a failure to remedy within the time given. Repudiation is the exception. Do not rely on a contract lapsing on its own. 

What is specific performance? 

A court order requiring the defaulting party to actually perform the contract, to settle. It is not the resale mechanism, which is a separate remedy where the seller terminates and resells and claims any shortfall. 

Can a seller keep a deposit larger than 10 per cent? 

Generally not the whole of it. If the deposit exceeds 10 per cent of the purchase price, the seller may forfeit only the part up to 10 per cent, and the rest is treated differently under the contract. 

The bottom line 

A refusal to complete is the one situation where the numbers stop being predictable, so it is the one where doing it yourself is most dangerous. Nothing happens automatically, the notices have to be exactly right, the deposit is not a cancellation fee, and the resale

mechanism gives a walking-away buyer no upside and real downside. If you are anywhere near this, on either side, get a property lawyer involved before you issue a notice, refuse access, or withhold a deposit. The cost of that advice is almost always smaller than the cost of getting it wrong. 

Truth. Strategy. Sold. 

If you would like a free appraisal for your property, please enquire via the form on our ‘Book a Free Appraisal‘ page.

About the author: Brendan Leahy has been selling homes throughout the Perth Hills and Foothills since 2002, with more than 1,500 personal sales. 

General information only, not legal advice. If a default notice is being considered or received, get advice from a property lawyer immediately.

What Stays With the House When You Sell in Western Australia?

You have sold the house, settlement is getting close, and then somebody asks the question no one thought to settle properly at the start.

Does the dishwasher stay? What about the curtains, the television bracket, the garden shed, the security cameras, the pot plants, the bore equipment or the expensive light fitting in the dining room?

These questions sound minor until a buyer arrives after settlement and discovers something they reasonably expected to receive has disappeared.

After more than two decades and more than 1,500 personal sales, I can tell you most arguments over what stays and what goes are avoidable. The problem is usually not dishonesty. It is two people making different assumptions about the same item. If an item matters to either the buyer or the seller, put it in the contract. Do not rely on what seems obvious.

This article is general information, not legal advice. Whether a particular item is a fixture or
a chattel can depend on how it is attached, why it is attached, the contract wording and the
surrounding circumstances. If an item is valuable or disputed, obtain advice before signing.

The simple rule of thumb: turn the house upside down

One of the simplest ways agents are taught to explain fixtures and chattels is this. If you could turn the house upside down and shake it, whatever falls out is generally a chattel. Whatever stays attached is generally a fixture.

That is not the complete legal test, but it is a useful starting point. As a general rule, an item that is screwed, nailed, glued, concreted or otherwise permanently fixed to the home or land will usually be treated as a fixture, and things planted in the ground ordinarily remain with the land. An item that is free-standing and easily movable will usually be a chattel.

The trouble is the grey area. A dishwasher can be connected to plumbing and power but still be removable. A large shed can look permanent without being fixed to a slab. Curtains are removable, while their tracks are fixed. A television is movable, while its wall bracket may stay. That is why the rule of thumb helps, but the contract is what removes the doubt.

Fixtures usually stay; chattels usually go

WA Consumer Protection describes chattels as movable items that are not part of the land
or building, and fixtures as items fixed to or forming part of the property. Its guidance is that fixtures generally remain while chattels are removed, unless the contract says otherwise.

Common fixtures include fixed floor coverings, light fittings, built-in air conditioning, fixed mirrors, television aerials, permanently installed sheds and plants growing in the ground. Common chattels include rugs, free-standing furniture, removable appliances, pot plants and other loose items.

Those are only examples. The classification of a particular item can still depend on its method and purpose of attachment, which is exactly why the safest practice is to list any uncertain item clearly in the Offer and Acceptance.

What we put in every contract

To remove the most common arguments, every Offer and Acceptance we prepare includes wording to the effect that the offer includes all fixed floor coverings, window treatments, light fittings and the dishwasher in place.

If the seller wants to keep one of those, it is excluded in writing before the buyer signs. If the buyer expects an unusual movable item, it is included in writing. For a valuable appliance, the brand and model can be recorded too. Those few words save a lot of misunderstanding at settlement.

The contract beats the assumption

A seller can generally exclude an item that might otherwise stay, provided the exclusion is clear and accepted as part of the contract. A buyer can also negotiate for a movable item to be included. For example:

  • Included in the sale: Bosch free-standing dishwasher, model ABC123.
  • Excluded from the sale: dining-room pendant light. The seller will remove it before settlement and install a standard working light fitting in its place.

The more valuable or unusual the item, the more specific the wording should be.

The items that cause the most confusion

Dishwashers.

A fully integrated unit can look like part of the kitchen, while a free-standing one is easy to remove. WA guidance specifically identifies dishwashers as items to list, and our contracts include the dishwasher in place unless agreed otherwise.

Curtains, blinds and window treatments.

Tracks, rods and fitted blinds are attached to the building. Curtains themselves can usually be removed. Because expectations differ, our standard wording includes window treatments unless the contract states otherwise.

Televisions and wall brackets.

The television normally belongs to the seller unless expressly included. A fixed bracket may remain, and if it is being removed, agree what happens to any holes or damage.

Sheds, cubby houses, aviaries and animal enclosures.

This matters throughout the Perth Hills and Foothills. Some structures are concreted or fixed, others can be moved. If it appears in the marketing and matters to either side, identify it in the contract.

Solar panels, batteries and EV chargers.

Roof-mounted panels and permanently installed equipment ordinarily appear to form part of the property. The contract should also deal with any finance, lease, service agreement, cables, adaptors and account transfers.

Pool equipment.

Fixed pumps, filters and heating are different from loose cleaners, covers, rollers and accessories. List the removable equipment if the buyer expects to receive it.

Everything else follows the same logic, so record it rather than guess: fixed mirrors and
hung mirrors, sentimental light fittings, security cameras and smart-home hubs (including
the codes and accounts needed to run them), outdoor kitchens and pizza ovens, workshop
benches, statues, water features and established plants. If it matters to either side, one line
in the contract settles it.

A story from my first year in real estate

One of my earliest sales was a home in the Kelmscott hills. The sellers had come from England, and everything went smoothly through the contract and final inspection.

The property settled. Not long afterwards the buyer rang me and said, “Brendan, you had better come up here and have a look.”

When I arrived I could hardly believe it. The sellers had removed the carpets, curtains, blinds and light fittings. The home had been stripped back.

I called the seller and asked what had happened. His answer was completely genuine: “What do you mean? That is what we do in England.”

He honestly believed he had done the right thing. I had to explain that this was Western Australia, and more importantly, the contract specifically included the fixed floor coverings, window treatments and light fittings. They had to be returned and properly reinstalled.

Fortunately the buyer was easy-going and could see the funny side once it was explained. The sellers arranged for the items to be put back by qualified people, and it was resolved. The lesson was not that anybody was dishonest. It was that assumptions change from country to country, and person to person, and the contract is there to make the expectation clear.

A much more expensive lesson about internet advice

A later sale was not so easy.

The seller had a stove and oven that formed part of the property and were included in the sale. We explained repeatedly that they were fixtures under the contract and could not simply be removed.

By that stage, though, the seller had started relying on advice from online forums. It did not seem to matter what the agent or the other professionals said. She had found people online telling her what she believed she was entitled to do, and she made up her own mind.

When the buyer’s building inspector attended and took his normal photographs, the report showed the stove and oven had been dismantled and left in pieces, with the gas connection cut. The matter had to move into the legal channel before settlement. The appliances had to be reinstated properly, and the delayed settlement exposed the seller to default interest under the contract.

That is where it gets expensive. On a seven-figure sale, with an outstanding balance well over a million dollars, default interest adds up fast. The 2022 Joint Form sets default interest at 9 per cent a year, calculated daily, though the form is updated from time to time and the rate that applies should always be confirmed against the current contract. On an outstanding balance of around 1.3 million, 9 per cent works out to roughly 320 dollars a day. A delay of a couple of weeks can add several thousand dollars, before any legal and trade costs on top.

The lesson is not “never use the internet.” It is that general online advice does not know your signed contract, your property or the facts of your transaction. Licensed agents, settlement agents and property lawyers are not infallible, but they are dealing with the actual transaction in front of them. Where the agent, settlement agent and lawyer are all telling you the same thing, an anonymous online opinion should not override the contract you signed.

Advertising photographs do not decide what is included

Buyers sometimes assume everything in the marketing photographs will remain. That is unsafe. Photographs normally show furniture, artwork, rugs, lamps, outdoor furniture, pot plants and decorative items that belong to the seller.

Marketing photographs do not, by themselves, reliably establish what is included in the sale. The contract is what identifies inclusions and exclusions. At the same time, advertising must still accurately represent the property and should not create a misleading impression about a significant feature that will be removed. If a major feature shown in the campaign is going to be removed, the safest approach is to declare it before offers are made.

What sellers should do before launching

Before photography and home opens, walk through the property with your agent and identify anything you intend to take that a buyer may reasonably think belongs to the property: sentimental light fittings, curtains and custom window treatments, dishwashers and appliances, wall-mounted televisions and brackets, security and smart-home equipment, sheds and enclosures, pool equipment, workshop benches, EV charging equipment, statues, water features and established plants.

Where practical, remove or replace the item before the photography. That is cleaner than presenting the home with an attractive feature and announcing later that the buyer does not receive it.

What buyers should do before making an offer

During the inspection, ask one question: what do I expect to still be here when I receive the
keys? If something matters, tell the agent before the offer is written. A verbal conversation is not a substitute for clear contract wording. Pay particular attention to window treatments, the dishwasher and appliances, TV brackets and fixed mirrors, security and smart-home equipment, sheds and outdoor structures, pool equipment, bore, rainwater and reticulation equipment, solar and EV charging, and any valuable plants or garden features.

Keys, garage remotes and access devices must be handed over

The sale is not complete in a practical sense if the buyer receives the house but cannot properly access or operate it. The Joint Form of General Conditions deals with the handover of keys and relevant remotes or access devices, and “access device” is defined to include keys, security devices and the codes for any security system. Sellers should collect and hand over everything reasonably required to enter and use the property, subject to the
exact contract terms: front, rear and side-door keys, security-screen keys, mailbox keys, shed and workshop keys, garage-door and gate remotes, and alarm fobs, access cards and relevant codes.

Brendan’s tip for sellers: create a settlement box

As soon as the property goes under offer, start a small box or drawer for everything that needs to stay with the home: all keys and labelled spares, garage and gate remotes, alarm fobs and access cards, instruction manuals, warranties and service records, smart-home reset or transfer instructions, spare remote batteries, and any agreed equipment or accessories. By settlement day everything is in one place, and there is no frantic search through packed boxes.

Brendan’s tip for buyers: change the locks after settlement

This is not a legal requirement, but I recommend it to almost every buyer. Once the property has settled, consider having a locksmith re-key the external locks. The first reason is convenience. Older homes often have a different key for every door, and a locksmith can frequently change the barrels so one or two keys operate the whole home. The second is security. You do not know how many copies of the old keys exist, or who may still have one. Previous owners may have given keys to relatives, neighbours, tradespeople, cleaners or house sitters over many years. Re-keying means you know exactly who can access your new home. As a rough guide it is commonly around 300 to 600 dollars depending on the number and type of locks, so get a current locksmith quote rather than treating that as fixed pricing.

What happens if something disappears before settlement?

The final inspection is your chance to check the property remains in the required condition and the seller has complied with the contract. If something is missing:

  1. Record exactly what is missing or altered.
  2. Take photographs where appropriate.
  3. Do not argue at the property.
  4. Notify the settlement agent and selling agent in writing.
  5. Let the settlement agents deal with it under the contract.

Depending on the item and the contract, the solution might be its return, replacement, repair of removal damage, an agreed settlement adjustment or legal advice. A missing item does not automatically entitle a buyer to cancel settlement. The contract and the seriousness of the breach matter.

Five practical things to do on settlement day

  1. Confirm all keys, remotes, fobs and access codes have been received.
  2. Walk through the home and confirm the agreed inclusions are present.
  3. Photograph the electricity, gas and water meter readings for your records.
  4. Confirm utility and internet arrangements.
  5. Book a locksmith to re-key the external locks.

Frequently asked questions

Does the dishwasher stay when you sell a house in WA?

It depends on the contract. WA guidance specifically flags dishwashers as items to list, because an integrated unit can look built-in while a free-standing one is easy to remove. Our contracts include the dishwasher in place unless it is expressly excluded, so the safest thing is to have it written in either way.

Do curtains and blinds stay when you sell in WA?

Curtain tracks, rods and fitted window treatments may appear to form part of the property, while curtains and some blinds can be readily removed. WA Consumer Protection actually lists curtains and blinds among its examples of chattels, and recommends identifying window fittings in the contract because expectations can differ. Our contracts include window treatments unless they are expressly excluded, which removes the argument before it starts.

Can a seller remove fixtures before settlement?

A seller can keep an item that might otherwise stay only if it is clearly excluded in the contract and accepted before the buyer signs. Removing a fixture that the contract includes is a breach, and it can lead to reinstatement, an adjustment, delayed settlement and default interest.

What is the difference between a fixture and a chattel?

A fixture is attached to or forms part of the property and generally stays. A chattel is a movable item that is not part of the land or building and generally goes. The rule of thumb: shake the house, what falls out is usually a chattel, what stays attached is usually a fixture. The contract settles anything uncertain.

The bottom line

The legal difference between a fixture and a chattel matters. But the best transaction is not the one where somebody wins an argument about it after settlement. It is the one where the argument never happens.

If the seller wants to keep it, exclude it in writing. If the buyer expects to receive it, include it in writing. One extra line in the Offer and Acceptance can save days of stress, damaged goodwill, trade costs, default interest and legal expense over an item worth a fraction of the property itself.

After more than 1,500 personal sales, my advice is simple: never assume the other side sees an item the same way you do. Put it in the contract.

If you are buying or selling in the Perth Hills or Foothills and want the process explained in plain English before you sign, get in touch.

To help you, please feel free to download our property sale checklist

Truth. Strategy. Sold.

About the author: Brendan Leahy has been selling homes across the Perth Hills and
Foothills since 2002, with more than 1,500 personal sales.

This article is general information only and is not legal advice. The classification of an item
and the remedies available may depend on the method and purpose of attachment, the
contract wording and the particular circumstances. Speak with your settlement agent or
property lawyer if an item is valuable, disputed or unclear